Retail banks don’t build real estate wealth; they choke it with red tape and rigid W-2 underwriting formulas. When you’re trying to build serious equity in Southern California, partnering with a dedicated investor focused mortgage broker Claremont CA investors trust makes the difference between winning a high-margin deal and watching your timeline fall apart. You already know the frustration of bringing a strong, cash-flowing asset to a retail branch, only to hit an arbitrary debt-to-income wall because the underwriter ignores rental upside and ADU potential.
Discover how an investor-focused mortgage broker in Claremont, CA structures specialized capital to scale your portfolio without getting trapped by personal tax write-offs. We’ll show you how agile tools like DSCR loans, fix and flip capital, and Non-QM leverage keep your acquisitions moving across Claremont, San Dimas, and Upland while legacy lenders remain stalled in paperwork.
Key Takeaways
- Learn why conventional retail bank formulas stall real estate portfolios and how asset-based debt bypasses personal tax write-off limitations.
- Discover the specific vetting questions you must ask to secure an investor focused mortgage broker Claremont CA deals require for fast execution.
- Compare aggressive leverage tools side-by-side, including DSCR Loans, Fix and Flip Loans, and Non QM Loans engineered around property cash flow.
- Pinpoint regional profit drivers across the Claremont and Inland Empire border, leveraging student rental density and value-add equity plays.
- Master the exact deal packaging steps needed to present pro-forma numbers cleanly and close before competing capital steps in.
Why Claremont Real Estate Investors Hit Brick Walls with Retail Banks
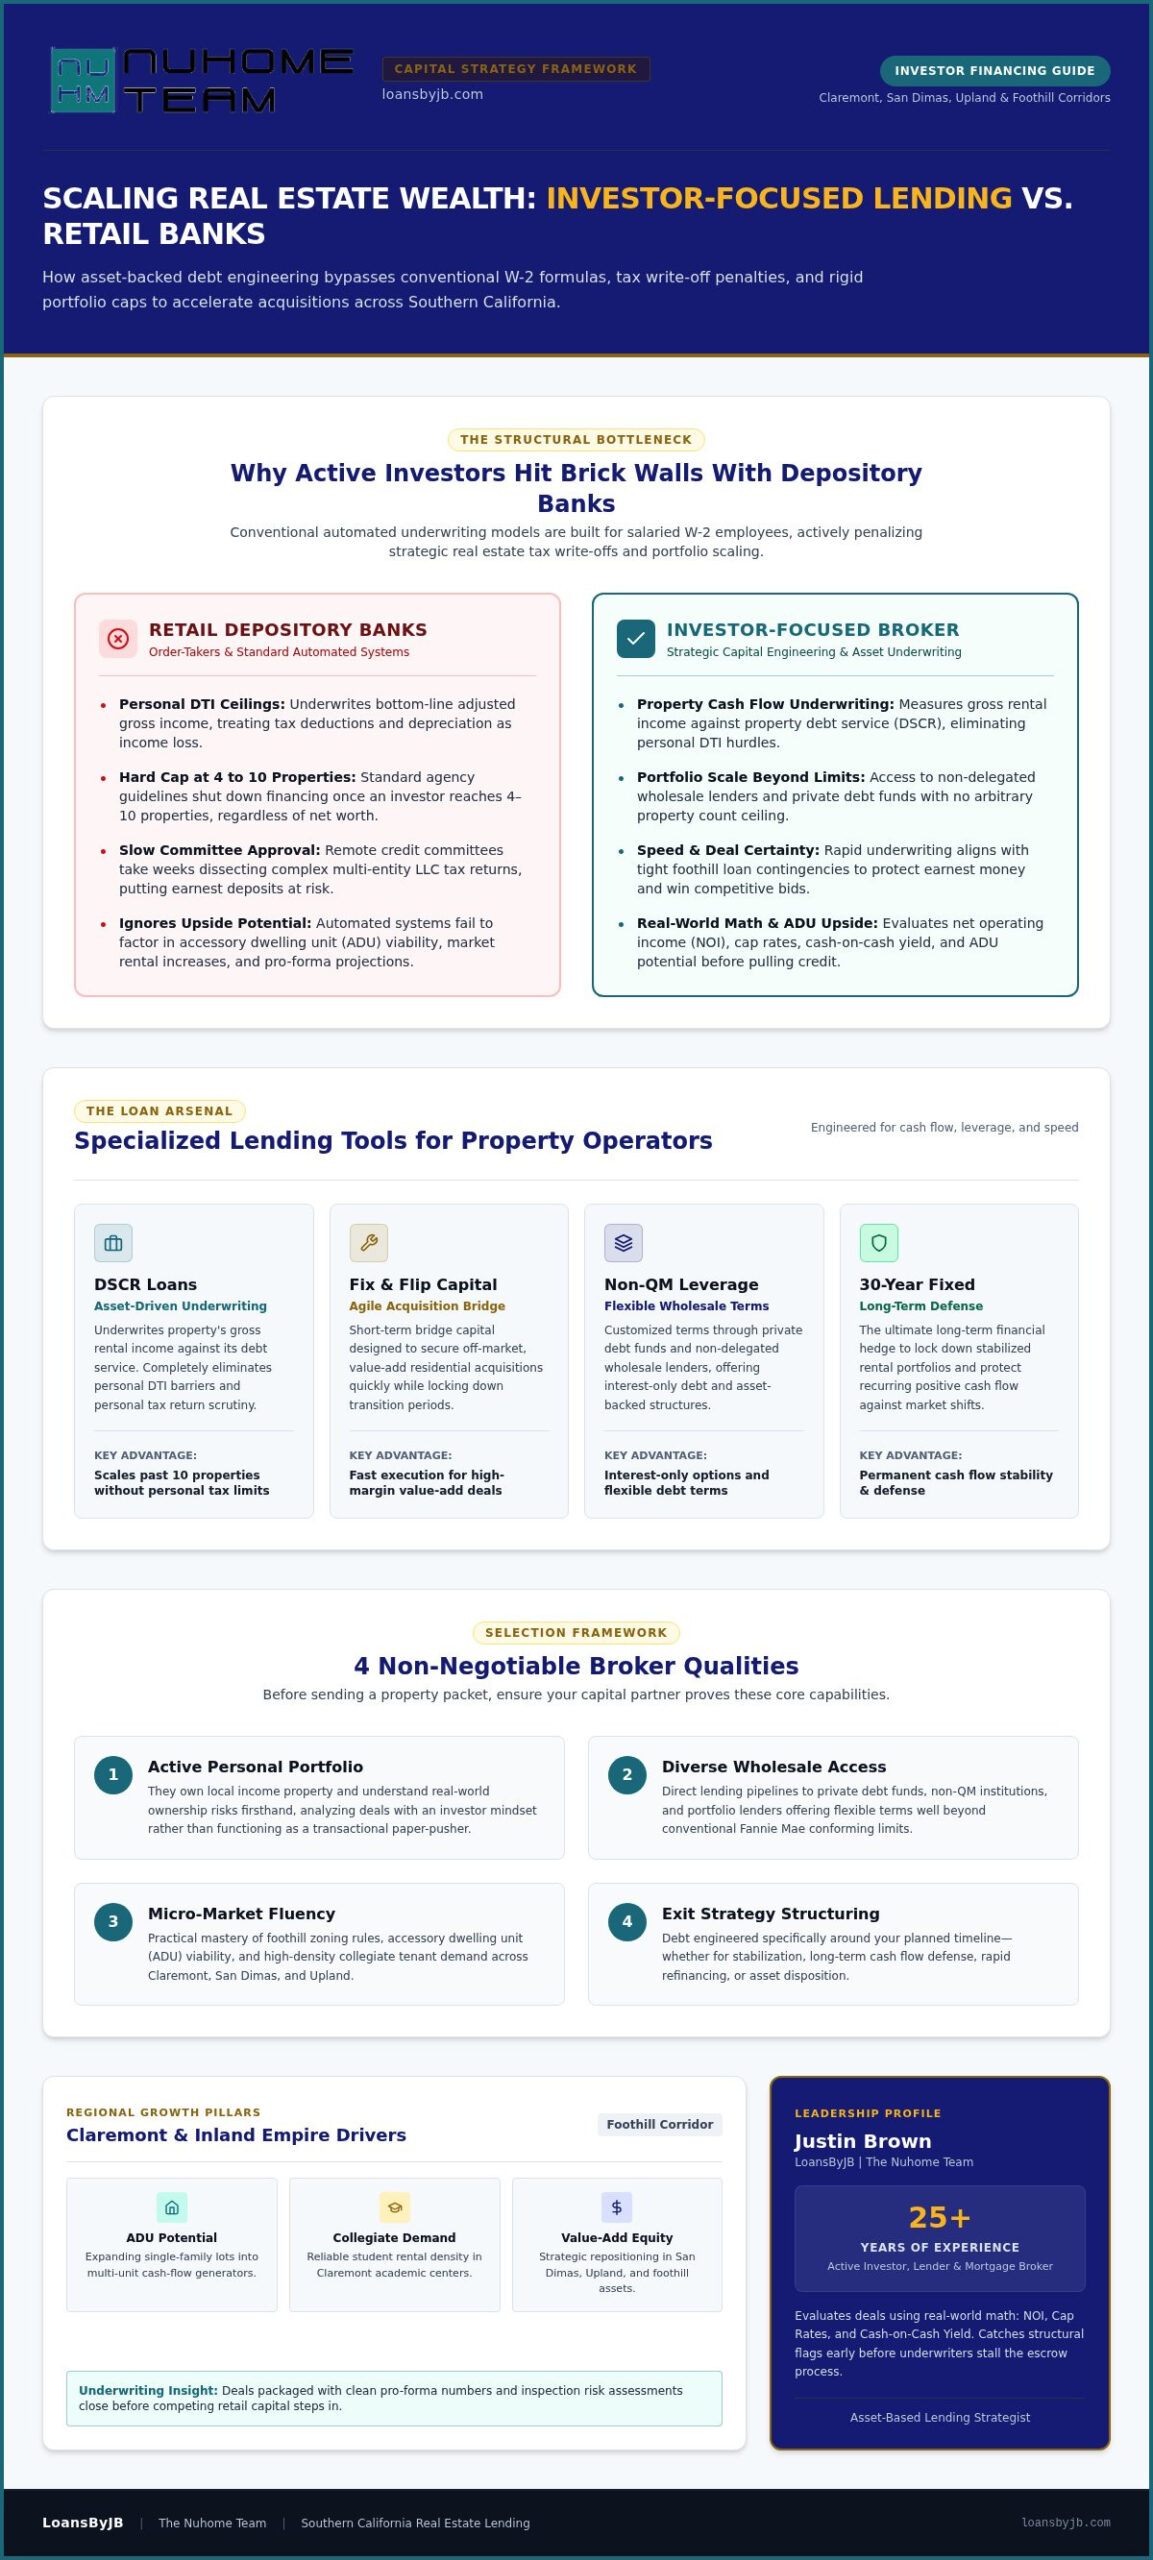
Walk into a traditional depository bank in Claremont, and you’ll speak with a retail loan officer programmed for salaried W-2 borrowers. They punch numbers into rigid automated models and pray Fannie Mae approves the file. When active real estate investors show up with complex tax strategies, multi-entity LLCs, and multiple rental properties, these institutions hit an immediate wall. A licensed mortgage broker working specifically with investors acts differently. Instead of functioning as an order-taker, a true investor focused mortgage broker Claremont CA operators rely on serves as a capital strategist, engineering debt around asset performance rather than personal tax returns.
The Trap of Traditional Debt-to-Income Calculations
Smart real estate operators use every legal deduction, write-off, and accelerated depreciation strategy to minimize taxable income. It’s smart tax planning. Unfortunately, retail branch underwriters see it as financial weakness. They evaluate your bottom-line adjusted gross income, apply conventional debt-to-income (DTI) ceilings, and declare you unqualifiable.
Worse, standard agency guidelines choke investors once they accumulate four to ten financed properties. Depository banks simply stop lending, regardless of your net worth or cash reserves. You shouldn’t have to choose between a smaller tax bill and scaling your rental footprint. Specialized products like Non QM Loans and DSCR Loans bypass this friction entirely by underwriting the property’s gross rental income against its debt service, eliminating the personal DTI barrier.
Speed and Deal Certainty in the San Gabriel Valley
Claremont and the surrounding foothill corridors demand swift execution. Sellers expect tight loan contingency periods, especially when evaluating competing bids on value-add residential assets. Retail branch managers have zero authority to overturn an automated underwriting system condition, and their remote credit committees take weeks to dissect basic business tax returns.
When an underwriter miscalculates market rents or questions self-employment write-offs three weeks into escrow, your earnest money deposit is on the line. Delayed commitments kill deals. Aligning with an investor focused mortgage broker Claremont CA dealmakers trust ensures lending decisions happen with speed, protecting your earnest money and securing competitive foothill acquisitions before other buyers catch up.
Criteria for Choosing an Investor Focused Mortgage Broker in Claremont CA
Most online directories rank loan officers by proximity and consumer reviews, completely ignoring execution capability. When vetting a mortgage broker, you need a disciplined framework that filters out retail order-takers. An exceptional investor focused mortgage broker Claremont CA operators rely on must prove four non-negotiable qualities before you ever send over a property packet:
- Active personal portfolio: They own local income property and understand real-world ownership risks firsthand.
- Diverse wholesale access: Direct lines to private debt funds, non-QM institutions, and portfolio lenders.
- Micro-market fluency: Practical mastery of foothill zoning, accessory dwelling unit (ADU) viability, and collegiate tenant demand.
- Exit strategy structuring: Engineering the loan around your planned stabilization, refinance, or disposition timeline.
Investor Mindset vs. Transactional Paper Pusher
A transactional originator looks at your tax returns; an investor peer analyzes the deal. You need a partner who evaluates net operating income, capitalization rates, and cash-on-cash yield before pulling credit. They review inspection reports early to catch structural flags before an underwriter demands costly repairs. Justin Brown brings over 25 years of hands-on experience as an active investor, lender, and broker, giving you an advocate who underwrites opportunities using real-world math.
Wholesale Lending Reach Beyond Agency Conforming Limits
Fannie Mae limits shouldn’t dictate your portfolio growth. Seasoned brokers maintain relationships with non-delegated wholesale lenders offering flexible portfolio debt, interest-only options, and asset-backed terms. While fast bridge capital secures off-market acquisitions, locking down a permanent 30 year fixed mortgage remains an indispensable strategy for long-term cash flow defense.
Deep Foothill Community Knowledge
Claremont features unique historic districts, strict architectural standards, and multi-tenant student demand driven by The Claremont Colleges. An appraiser unfamiliar with local boundaries might pull comps from San Dimas or Upland that misprice rental revenue on Indian Hill Boulevard. Your financing team must understand these foothill micro-markets and coordinate seamlessly with local escrow and title desks. If you want capital matched to your exact balance sheet, connect directly with LoansByJB to review your financing roadmap.
The Investor Loan Arsenal: Comparing Strategic Financing Products
Savvy real estate operators match debt directly to the property life cycle. A fixer-upper near Arrow Highway requires a completely different capital structure than a stabilized fourplex near the Claremont Village. Deploying diverse strategic financing products allows you to conserve liquid reserves, bypass personal income roadblocks, and seize quick turnaround opportunities. An experienced investor focused mortgage broker Claremont CA operators rely on engineers custom debt stacks, ensuring short-term acquisitions transition seamlessly into long-term wealth generators.
DSCR Mortgages for Frictionless Rental Scaling
Asset-based lending rewires underwriting rules in your favor. Instead of scrutinizing personal tax returns or W-2 paystubs, Debt Service Coverage Ratio financing evaluates the subject property’s real-world rental yield against its monthly carrying cost. If projected or in-place rents cover the principal, interest, taxes, and insurance (PITI), the deal is viable. You can scale beyond conventional agency caps without hitting personal debt ceilings. Explore execution strategies inside our dscr loan guide to review qualification benchmarks.
Bridge, Hard Money, and Fix-and-Flip Debt
Distressed residential properties rarely wait for sluggish banking committees. When off-market sellers demand a strict ten-day escrow, private leverage secures your pipeline. Fix and Flip Loans and asset-backed bridge options provide urgent liquidity, funding both the acquisition and capital expenditures. Always underwrite debt costs against verified after-repair value (ARV) to protect gross margins. Discover how to deploy short-term capital effectively using hard money loans across competitive San Gabriel Valley pockets.
Renovation and Value-Add Construction Programs
Properties with severe deferred maintenance often fail traditional condition guidelines, killing standard retail financing on arrival. Homestyle Renovation Loans solve this hurdle by bundling purchase and rehab funding into a single long-term closing. For investors house-hacking a multi-family property as an owner-occupant, an fha 203k loan delivers accessible entry leverage. When expanding density through detached ADUs or complete structural transformations, dedicated construction loan programs supply staged draws to maximize your site’s physical yield.
Navigating Claremont and Inland Empire Investment Property Strategies
Claremont sits in a rare sweet spot on the eastern edge of Los Angeles County. It pairs affluent foothill stability with direct access to high-yield Inland Empire rent corridors. Acquiring rental assets here requires distinct tactics compared to standard suburban investing. Working alongside a skilled investor focused mortgage broker Claremont CA dealmakers trust allows you to capitalize on three dominant local profit drivers:
- Collegiate academic housing: Seven contiguous campuses delivering persistent, premium per-room rental demand.
- Substantial parcel footprints: Expansive single-family residential lots primed for accessory dwelling unit (ADU) density.
- Cross-county border dynamics: Blending premium LA County equity growth with aggressive cash-flow opportunities across Upland and San Bernardino County.
Student and Academic Faculty Rental Demographics
The Claremont Colleges create a steady tenant ecosystem of faculty, researchers, and upper-division students. Properties within biking distance of Dartmouth Avenue or Claremont Village command aggressive rent premiums. When analyzing shared-living layouts, keep municipal street-parking regulations and overnight enforcement strictly in view. Structure reserve accounts intentionally to absorb seasonal turnover during June and July before fall leases reset.
ADU Construction and Lot Density Plays
Foothill parcels frequently feature deep backyards and alley access, offering ideal geometry for detached accessory units. State density legislation makes adding secondary square footage simpler than ever. Structuring short-term construction financing or hard money bridge debt funds the build without draining capital reserves. Once the second unit is permitted and occupied, we recalculate debt service coverage metrics to execute a seamless cash-out refinance into permanent debt.
Corridor Synergies: Upland, San Dimas, and Glendora
Savvy operators do not stop at the city limit. Bordering municipalities provide complementary risk-adjusted returns along Interstate 210 and Route 66. While Claremont delivers institutional prestige and consistent equity preservation, adjacent submarkets offer attractive entry pricing for duplexes and fourplexes. To capitalize on these regional dynamics with cross-county lending versatility, contact LoansByJB to structure your next foothill acquisition.
How to Vet Your Broker and Secure Capital with LoansByJB
Most retail portals sell your contact information to automated call centers. That model fails active investors who need fast, definitive underwriting decisions. Vetting an investor focused mortgage broker Claremont CA dealmakers can rely on means probing beyond basic licensing. You must test their technical agility under real pressure before submitting a live property file.
The Five Questions Every Investor Must Ask Their Broker
Put your prospective originator through a rigorous interview before opening escrow. Demand direct, unambiguous answers to these five operational questions:
- How many DSCR or Non QM Loans have you personally closed within the past twelve months?
- How do your wholesale capital sources underwrite unpermitted square footage or properties requiring immediate habitability repairs?
- Do you fund through restricted internal balance sheets or tap diverse wholesale debt desks across the country?
- What prepayment penalty schedules apply to your medium-term bridge versus 30-year permanent options?
- Can you issue a binding conditional loan commitment without sending tax returns through an automated agency engine?
Building Your Investment Financing Dossier
Speed in underwriting comes from thorough upfront preparation. Presenting a professional deal package sets a decisive tone with credit committees. Assemble an airtight dossier containing your LLC operating agreement, EIN confirmation letter, and relevant corporate filing certificates. Include clean rent rolls, signed leases, and realistic pro-forma numbers detailing realistic rehab scopes. Demonstrating verified liquid reserves upfront immediately unlocks tier-one leverage and preferred pricing schedules.
Initiating Your Deal Review with LoansByJB
Justin Brown and LoansByJB (The Nuhome Team) operate under NMLS #1647915. With over 25 years of hands-on experience as an active investor, lender, and broker, Justin evaluates every transaction through the lens of real-world equity returns. He has funded thousands of complex Southern California mortgage scenarios, navigating intricate tax write-offs, cross-collateralization, and multi-parcel expansions with ease.
Stop letting traditional depository banks stall your momentum. When you bring an opportunity to LoansByJB, you receive a direct, zero-fluff analysis of your debt options. Call Justin Brown directly to structure custom leverage tailored to your Claremont balance sheet, turning complex property scenarios into funded acquisitions.
Scale Your Foothill Real Estate Portfolio with Strategic Capital
Retail banking guidelines will always choke an active investor’s momentum. Rigid debt-to-income caps and tax write-off penalties shouldn’t dictate how fast you build equity. Scaling a high-performing rental footprint across Claremont, San Dimas, and Upland demands debt structures engineered around asset performance and speed. Aligning with a dedicated investor focused mortgage broker Claremont CA dealmakers trust gives you the strategic leverage needed to beat out conventional buyers and expand your balance sheet.
Justin Brown brings over 25 years of active experience as an investor, lender, and broker, with thousands of complex Southern California transactions successfully funded. You gain direct access to institutional wholesale capital, specialized Non QM Loans, and agile private money funds designed for real-world returns. Don’t let bureaucratic delays sideline your next acquisition. Take decisive action on your terms. Discuss your next investment deal with Justin Brown at LoansByJB and secure the capital your portfolio deserves.
Frequently Asked Questions
What makes an investor focused mortgage broker different from a standard loan officer?
An investor-focused broker underwrites deals based on property yield, debt service coverage, and exit strategies rather than conventional W-2 guidelines. Standard retail loan officers push single-lender balance sheet products designed for primary residences. A seasoned investor focused mortgage broker Claremont CA operators turn to acts as a capital architect. They maintain direct wholesale relationships with Non QM lenders, private money desks, and bridge capital sources built to fund complex entity structures.
Can I buy a rental property in Claremont using a DSCR loan without showing personal tax returns?
Yes, DSCR loans require zero personal tax returns, W-2 forms, or employment verification. The underwriting decision hinges entirely on the subject property’s cash flow potential and your credit score. Lenders compare the property’s gross rental income against its total monthly carrying costs, including principal, interest, taxes, and insurance. As long as the rental revenue meets the minimum debt-coverage benchmark, personal write-offs won’t hold you back from acquiring high-equity foothill properties.
How fast can an experienced Claremont mortgage broker close on an off-market deal?
A private capital or hard money loan can close in as little as 7 to 10 business days when paperwork is organized. Permanent non-QM financing, such as DSCR loans, typically requires 21 to 30 days depending on appraisal timelines across Los Angeles and San Bernardino counties. Working with an experienced local broker ensures title, escrow, and appraisal desks align upfront, eliminating unexpected conditions and preventing lost earnest money deposits.
Are mortgage brokers in Claremont able to finance properties with unpermitted additions or ADUs?
Yes, brokers have access to specialized Non QM and private lending programs that finance properties with unpermitted space. Retail depository banks usually reject these properties immediately. A specialized broker matches the scenario with wholesale lenders who either lend based on the permitted square footage or evaluate the unpermitted footprint through an as-is valuation. If you plan to legalize or convert space, short-term bridge or construction financing bridges the gap smoothly.
What minimum down payment is typically required for investment property loans in Southern California?
Down payments for investment properties in Southern California generally range from 15% to 25%, depending on credit score and property type. Certain DSCR programs allow purchases with up to 85% loan-to-value for well-qualified borrowers with strong liquidity reserves. If you are pursuing a value-add property using Fix and Flip Loans or private capital, lenders frequently finance up to 90% of purchase costs alongside 100% of the renovation budget.
Can I finance both the purchase price and renovation costs into a single mortgage in Claremont?
Yes, you can combine purchase and improvement funds into a single transaction using Homestyle Renovation Loans or specialized Fix and Flip Loans. This approach avoids draining your cash reserves on heavy repairs. Underwriters base the loan amount on the property’s anticipated after-repair value (ARV) rather than its distressed purchase condition. Funds for construction are held in escrow and released across pre-scheduled draw inspections as your contractors finish each phase.
Why do real estate investors prefer independent wholesale brokers over major national banks?
Independent brokers shop dozens of competing wholesale lenders instead of forcing you into one narrow underwriting box. Major national banks focus heavily on retail consumer banking and standard Fannie Mae guidelines that penalize self-employed borrowers. Partnering with an investor focused mortgage broker Claremont CA investors rely on gives you access to flexible debt desks, customized DSCR parameters, and agile decision-makers who evaluate real estate with an investor mindset.
Need the mortgage math checked?
Talk through the loan before you guess.
Use the estimator, request a refinance quote, or book a call with The Nuhome Team. We will help you compare the options that actually fit the file.
This is not a commitment to lend. Approval, terms, and pricing depend on credit, income, assets, property, and program guidelines.