The most expensive loan you’ll ever take is the one that costs you the deal. Many investors look at double-digit interest rates and see a burden. Savvy pros see a tactical equity-multiplier. You’ve felt the sting of losing a prime property in Southern California because a traditional bank took 45 days to clear underwriting. Leveraging hard money loans allows you to bypass that bureaucracy. Close with the speed of a cash buyer. Scale your portfolio while the clock is ticking.
I know the frustration of having a fix-and-flip project rejected because of rigid, outdated bank rules. You need capital that moves as fast as the market. I’ll show you how to master the mechanics of private lending to secure fast capital and outmaneuver the competition. Use debt as a tactical weapon to win more deals and maximize your leverage. It’s time to stop playing by the bank’s rules and start playing to win.
We’ll break down the bridge-to-permanent financing cycle. You’ll learn how to move from a quick close into long-term stability. From understanding LTV ratios to executing a seamless exit strategy, this is your roadmap. Stop waiting on bank approvals. Start closing deals on your own terms.
Key Takeaways
- Learn how hard money loans function as tactical equity-multipliers, allowing you to close deals with the speed and certainty of a cash buyer.
- Understand why asset-based lending focuses on property potential over personal credit history, bypassing the rigid restrictions of traditional banks.
- Master the math behind interest rates and points to ensure your fix-and-flip or BRRRR projects stay profitable while using maximum leverage.
- Discover the “investor lens” approach to underwriting that helps you accurately evaluate carrying costs and Southern California market values.
- Learn to execute the bridge-to-permanent financing cycle by transitioning short-term debt into long-term wealth through DSCR or 30-year fixed loans.
What is a Hard Money Loan and Why Do Investors Use Them?
Stop thinking of debt as a burden. Start seeing it as a bridge. Most banks treat you like a risk to be managed; we treat you like a partner with a deal. So, what is a hard money loan exactly? It is a short-term, asset-based loan secured by real estate. The “hard” refers to the physical asset. The property itself serves as the primary collateral. While a traditional lender obsesses over your debt-to-income ratios, a hard money lender focuses on the equity in the deal. If the property has value, the deal has life.
In real estate, speed is a currency. A 30-day bank approval is a death sentence for a distressed property deal. Sellers in competitive markets want certainty. They want to know the check will clear in days, not months. Closing in 7 days turns you into a cash-equivalent buyer. This speed allows you to outmaneuver competitors who are stuck in the underwriting mud. Beyond speed, it is about leverage. Why tie up $500,000 of your own cash when you can use ours? Keep your capital liquid. Scale your portfolio by doing three deals at once instead of one.
The Core Mechanics: Asset-Based Underwriting
Hard money lenders look at the property first and the borrower second. We use an “investor lens” to see what the bank misses. We prioritize the After Repair Value (ARV) because that is where the profit lives. ARV is the projected market value of a property after all renovations are completed. If your math is right and the exit strategy is solid, the capital is available. It’s about the potential of the asset, not just a snapshot of your current income.
Hard Money vs. Traditional Mortgages
The difference is night and day. Banks want a perfect paper trail and three years of tax returns. We want a solid deal and a clear exit. In Southern California markets like Rancho Cucamonga or Claremont, a 30-day wait is a deal-killer. Private capital allows you to say “yes” when the bank’s rigid rules force them to say “no.”
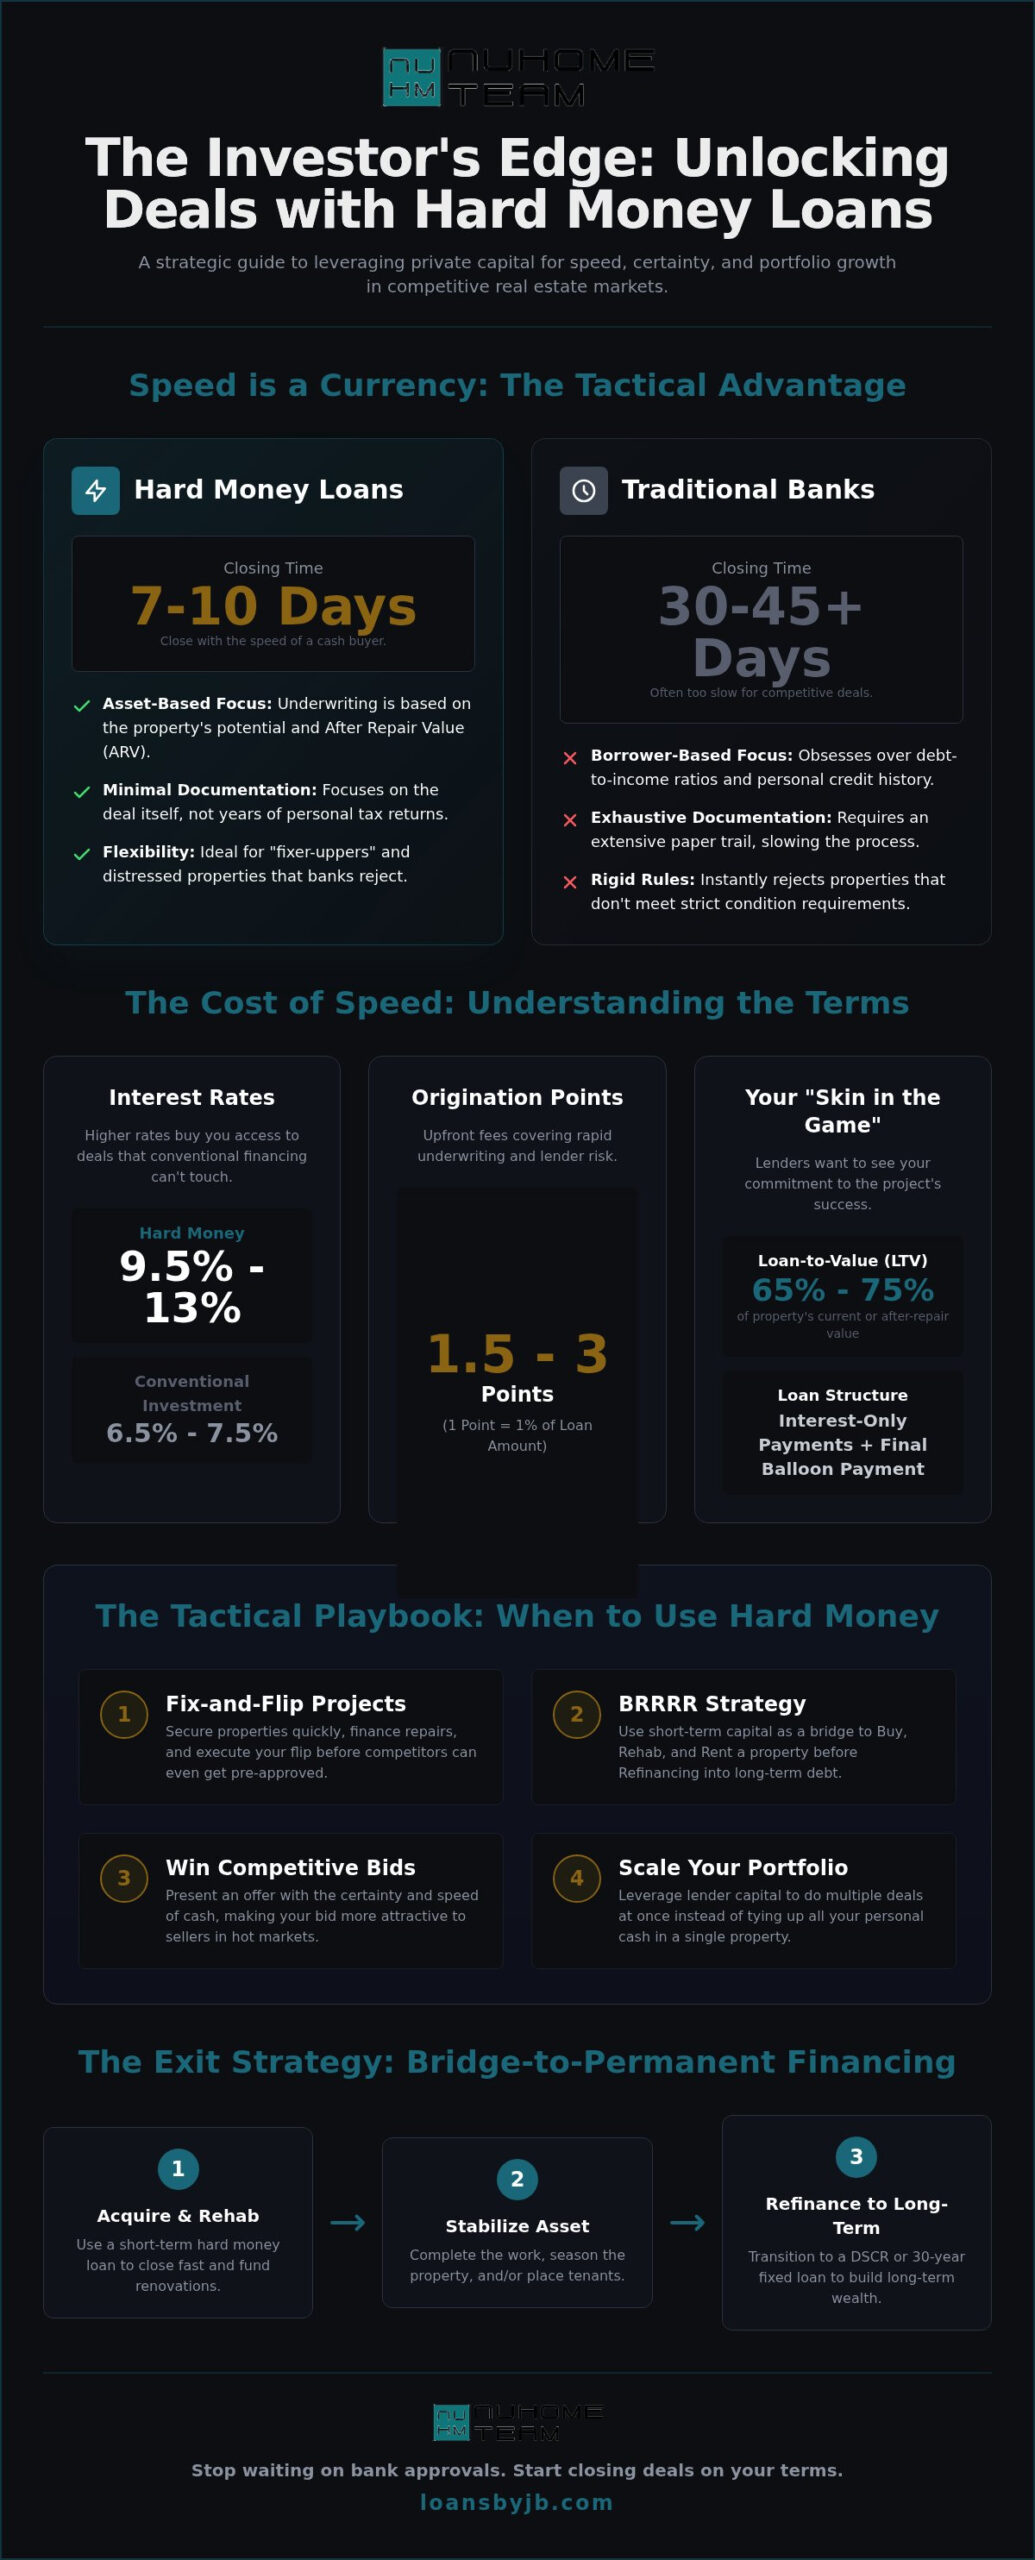
- Approval times: Traditional banks take 30 to 45 days. Hard money loans can fund in as little as 7 to 10 days.
- Documentation: Banks require exhaustive personal financial history. Private lenders look at property potential and your track record.
- Flexibility: We can finance “fixer-uppers” that traditional underwriters would reject instantly due to condition requirements.
The Cost of Speed: Understanding Rates, Points, and Terms
Stop comparing hard money loans to your primary residence mortgage. It’s a false equivalence. A traditional 30-year fixed loan is built for stability over decades. Hard money is built for velocity over months. Because these loans are short-term and carry higher risk for the lender, the interest rates are naturally higher. As of June 2026, interest rates for first-position hard money loans typically range from 9.5% to 13%. While conventional investment mortgages sit around 6.5% to 7.5%, the premium you pay for private capital buys you the ability to close deals that banks won’t touch.
You also need to account for origination points. These are upfront fees paid at closing, typically ranging from 1.5 to 3 points. One point equals 1% of the loan amount. This covers the lender’s overhead for rapid underwriting and the risk of funding a distressed asset. Understanding how hard money works for real estate investors means recognizing that these costs are simply line items in a profit-and-loss statement. If the deal doesn’t work with a 12% rate, it’s probably not a deal worth doing.
Lenders also look at your “skin in the game” through two lenses. Loan-to-Value (LTV) usually caps at 65% to 75% of the property’s current or after-repair value. Loan-to-Cost (LTC) measures the loan against the total project price, including purchase and rehab. Finally, prepare for the balloon payment. Most hard money loans are not amortized. You pay interest-only during the term, and the full principal balance is due on the maturity date. This is why your exit strategy is the most important part of the application.
Calculating the Real Cost of a Deal
Don’t let a 12% interest rate scare you away from a $50,000 profit. If you hold a loan for six months, that “high” interest rate only applies to half the year. Factoring in carrying costs, such as taxes, insurance, and utilities, is vital for your flip budget. We use an “investor lens” to help you evaluate if the speed of the capital justifies the cost. Often, paying for speed is the only way to beat a cash buyer to a high-margin property. Once the project is stabilized, you can often transition into a 30-year fixed mortgage to secure long-term equity.
Common Terms and Duration
Typical hard money terms last between 6 and 24 months. These are designed to be bridge solutions. Most investors opt for interest-only payments to maximize monthly cash flow while the property is under construction. Always check the fine print for prepayment penalties. Some lenders require a minimum of three to six months of interest, even if you flip the house in 30 days. Know your timeline before you sign the note.
Hard Money vs. Private Money: Decoding the Capital Sources
Investors often swap these terms like they’re identical. They aren’t. While both provide faster capital than a bank, the source of that capital changes your entire experience. Professional firms fund hard money loans using pooled capital or institutional lines of credit. Private money usually comes from an individual or a small group lending their own personal savings. One is a business transaction; the other is a relationship. If you’re serious about scaling, you need to know which one fits your deal.
Hard money offers a level of certainty that individual lenders can’t match. When you’re mid-flip in Rancho Cucamonga, you can’t afford for your lender to have a “change of heart” or a personal financial emergency. Professional lenders follow a structured playbook. They use formal appraisals and draw schedules to keep the project moving. Weighing the pros and cons of hard money loans often reveals that while private money might occasionally be cheaper, hard money is far more reliable for scaling a professional real estate business.
Professional Lenders vs. Individual Investors
Reliability is the deciding factor for serious pros. Professional firms don’t run out of money mid-project because their kid needs college tuition. They have dedicated departments for inspections and fund draws. This structure protects you as much as it protects them. It ensures the project stays on track and the money is there when the contractor finishes a phase. As a broker with an “investor lens,” Justin Brown helps you navigate these options to find the best fit for your specific deal in markets like Claremont or Glendora. We bridge the gap between institutional speed and local market intelligence. For a deeper look at how to source and vet capital for your next acquisition, explore our 2026 private money lender guide for Southern California investors.
Soft Money: The Middle Ground
Sometimes you don’t need the lightning speed of hard money, but you aren’t ready for a 30-year bank commitment either. Enter “soft money.” This is the middle ground. It offers lower interest rates than traditional hard money loans but requires more documentation. It’s the perfect fit for a property that is already stabilized or an investor with a high FICO score who still needs a quick close.
- Underwriting: Stricter than hard money; may require credit checks or limited income verification.
- The Benefit: Lower points and rates, making it more affordable for longer-term projects.
- The Trade-off: Slower funding times, usually taking 14 to 21 days instead of 7.
Choose soft money when you have a bit more breathing room and a stronger personal financial profile. It serves as an excellent bridge before you transition into a DSCR loan for long-term cash flow.
The Tactical Playbook: When to Use Hard Money
Hard money isn’t just a loan. It’s a tactical move. If you’re waiting on a 30-day bank approval, you’ve already lost the deal. Professional investors use hard money loans to seize opportunities that standard buyers can’t touch. Whether you’re gutting a kitchen or bridging the gap between a sale and a purchase, this is your leverage. It’s about having the right tool for the right job. Stop asking if the money is expensive. Start asking if the deal is profitable enough to justify the speed.
The classic use case is the Fix and Flip. You need capital for the purchase price and the renovation budget. Traditional lenders won’t touch a house without a working kitchen or a functional roof. We will. We fund the potential, not just the present state. Then there’s the BRRRR Method: Buy, Rehab, Rent, Refinance, Repeat. This strategy is the engine of portfolio growth. You use short-term capital to force appreciation, then pull your equity back out through a refinance. It’s a cycle that turns one property into ten without draining your personal savings every time.
Bridge financing is another essential play. Imagine finding a “must-have” deal before your current project has sold. You can’t let that opportunity slip. Hard money bridges that liquidity gap, allowing you to secure the new asset without waiting on a slow-moving escrow. Finally, consider distressed properties. These are the homes that fail FHA or VA inspections. While others see a disaster, you see a discount. We provide the capital to fix the “un-lendable” problems that scare away the retail market. You buy low, fix the issues, and create massive equity. If you’re a veteran navigating the Southern California market, understanding how a VA loan functions as a strategic wealth-building tool in 2026 can open doors that even hard money can’t match.
Winning in Competitive Markets
Southern California is a battlefield. To win in Rancho Cucamonga or Claremont, you need to act like a cash buyer. Hard money gives you that speed. You can close in days, beating institutional buyers who are bogged down by committees and red tape. It’s about moving faster than the market. We help you close the gap on properties with structural issues that would stall a bank for months. If you want to win, you have to be the most decisive person in the room. Speed is your greatest competitive advantage. Working with an experienced private money lender who knows the Southern California market is often the difference between landing the deal and watching it go to someone else.
The Crucial Exit Strategy
Never sign a note without a clear way out. The balloon payment is a hard deadline. Most pros choose one of three exits. You can sell the asset for a profit once the renovation is complete. If you want to build long-term wealth, you can refinance into a DSCR loan to keep the cash flow. This move pays off the hard money and locks in a lower rate. If the project was intended as your primary residence, you can transition to an FHA 203k loan to finish the equity conversion. Talk to Justin Brown today to map out an exit strategy that protects your profit and scales your portfolio.
Navigating the Hard Money Process with LoansByJB
You don’t need a lender who just cuts a check. You need a partner who understands the dirt. At LoansByJB, we apply an “investor lens” to every application. We don’t just look at numbers on a spreadsheet; we evaluate the deal’s actual viability. If the math doesn’t work, we’ll tell you. Our goal isn’t just to fund hard money loans. We want to ensure you have a profitable exit. Most banks want you to fail so they can take the asset. We want you to succeed so you can do ten more deals with us.
Local expertise isn’t a luxury in Southern California. It’s a necessity. Markets like Rancho Cucamonga and Claremont move fast. An appraiser from outside the area won’t understand the nuances of a specific neighborhood’s value. We do. We’ve spent decades in these streets. This local intelligence ensures your loan is structured correctly from day one. When the time comes to move from short-term debt to permanent financing, the transition is seamless. We help you bridge the gap into a DSCR loan or a 30-year fixed mortgage without the typical friction of switching lenders.
The Justin Brown Advantage
Experience matters. Justin Brown brings over 25 years of history as a broker, lender, and investor. He’s been on your side of the table. This isn’t a corporate call center experience. It’s a real conversation about property carrying costs, renovation timelines, and exit strategies. We optimize your loan structure today to ensure you pass future underwriting tomorrow. We know what long-term lenders want to see. We build your hard money file to meet those standards from the start.
Steps to Secure Your Hard Money Loan
We value your time. Our process is designed for speed and clarity. We move at the pace of the market, not the pace of a bank committee. Follow these steps to get funded:
- Initial Deal Review: Send us the property address, your purchase price, and a detailed rehab budget. We’ll give you a quote within 24 hours.
- The Real Conversation: We’ll discuss your specific goals. Are you flipping for a quick profit or building a rental portfolio? We align the terms with your timeline.
- Funding and Execution: Once the deal is vetted, we move to close. You get the capital you need to start the project and beat the competition.
Stop overthinking the process. If you have a deal that makes sense, we have the capital to back it. Get your 24-hour quote and start scaling your portfolio today.
Stop Waiting and Start Closing
Success in real estate belongs to the decisive. You now understand that hard money loans aren’t just expensive debt; they are tactical equity-multipliers. By focusing on the asset’s potential rather than your personal tax returns, you can bypass rigid bank bureaucracy and close deals with the speed of a cash buyer. Whether you’re executing a BRRRR strategy or a quick flip, the key is having a rock-solid exit strategy and a lender who speaks your language.
Don’t settle for a lender who doesn’t understand the Southern California market. Justin Brown brings over 25 years of experience as a broker, lender, and investor to your deal. We specialize in navigating the complex path from private capital to traditional refinancing, ensuring your project stays profitable from start to finish. It’s time to outmaneuver the competition and scale your portfolio with confidence.
Get a Real Investor Perspective on Your Next Deal
Your next project is waiting. Let’s get to work.
Frequently Asked Questions
Is a hard money loan a good idea for a first-time investor?
Yes, if the deal has enough equity to protect your downside. Hard money is an excellent tool for first-time investors because it focuses on the asset rather than your personal track record. While banks often demand years of experience, a private lender looks at the profit potential in the deal. It allows you to compete with seasoned pros by providing the same speed and certainty. Just ensure your exit strategy is airtight before you sign.
How fast can a hard money loan actually close in Southern California?
You can expect to close in as little as 7 to 10 days in Southern California. Traditional banks are bogged down by layers of bureaucracy that can take 45 days or more. Local lenders who understand the specific nuances of the Inland Empire or San Gabriel Valley move much faster. We streamline the underwriting process to match the speed of the market. This rapid funding turns your offer into a cash-equivalent bid sellers take seriously.
Do I need good credit to get a hard money loan?
You don’t need perfect credit to secure hard money loans, but your score still influences the final terms. Most lenders prioritize the property’s value and your equity position over your FICO score. However, borrowers with scores of 700 or higher typically access the most favorable interest rates and lower origination points. Even with lower credit, a deal with significant equity and a clear exit strategy will usually find a path to funding. If your credit profile is complex due to self-employment or business deductions, exploring non-QM loans designed for investors with non-traditional income may open additional financing options alongside hard money.
What happens if I can’t pay back my hard money loan on time?
Communication is your best defense if your project hits a snag. Most lenders prefer a loan extension over the headache of a foreclosure. If your renovation is delayed, reach out early to discuss extending the balloon payment. However, remember that these are asset-based loans. If you default and fail to provide a viable solution, the lender has the legal right to take the property to recoup their capital. Always have a backup plan.
Can I use a hard money loan for my primary residence?
No, you generally cannot use this type of financing for a primary residence. These loans are specifically designed for business purposes and investment properties. Federal regulations like the Dodd-Frank Act impose strict requirements on owner-occupied loans that most private lenders aren’t structured to handle. If you intend to live in the home, you should look into an FHA 203k renovation loan or a Homestyle renovation loan to cover your purchase and repair costs. Veterans in particular should explore how a VA loan can serve as a powerful alternative for owner-occupied purchases in California without the burden of a down payment or private mortgage insurance.
What is the typical down payment for a hard money loan in 2026?
Expect to put down between 20% and 35% of the purchase price in 2026. While some lenders offer higher leverage for experienced investors with a proven track record, most require significant skin in the game to mitigate risk. This down payment ensures you are committed to the project’s success. Your total out-of-pocket costs will also include origination points and closing fees. Having liquid reserves is essential for handling unexpected renovation costs. For investors looking to scale their portfolio through international property finance or private equity, click here to learn about development finance opportunities.
Lenders determine value by looking at both the current condition and the After Repair Value (ARV). We use local appraisals and recent market data to see what similar renovated homes have sold for in the immediate area. This “investor lens” approach focuses on the future potential of the property rather than its current state. It ensures the loan amount is supported by the actual profit you will realize upon sale or a future refinance. For investors evaluating deals in other competitive regions, Level 4 Funding provides expert valuation and funding support for the Arizona market.
Refinancing hard money loans into traditional mortgages is the standard exit strategy for long-term investors. Once you’ve renovated the property and placed a tenant, you can transition into a 30-year fixed mortgage or a DSCR loan. This move lowers your interest rate and secures your long-term cash flow. If your income structure doesn’t fit conventional lending guidelines, non-QM loans offer a flexible path to permanent financing for self-employed investors and entrepreneurs. We specialize in structuring your initial loan to ensure it meets the requirements for permanent financing when your project is complete.
Need the mortgage math checked?
Talk through the loan before you guess.
Use the estimator, request a refinance quote, or book a call with The Nuhome Team. We will help you compare the options that actually fit the file.
This is not a commitment to lend. Approval, terms, and pricing depend on credit, income, assets, property, and program guidelines.