Your tax return is a lie. It isn’t because you’re dishonest. It’s because the IRS and traditional mortgage lenders speak two different languages. You’ve spent years maximizing legal deductions, only to have a bank teller tell you that you don’t earn enough for a mortgage. It’s a broken system that punishes successful entrepreneurs. If you’re tired of rejection, it’s time to leverage non-qm loans to get the deal done.
Standard rules are built for W-2 employees with simple lives. They aren’t built for savvy investors. You shouldn’t be sidelined by rigid bureaucracy when you have the capital and the cash flow to grow your portfolio. You deserve a financing partner who looks at your actual bank statements, not just a bottom line on a tax form. We understand that your business expenses shouldn’t stop you from owning property.
This guide shows you how to bypass those outdated bank rules. You’ll discover how to secure high-value financing using your real income. We’re breaking down the 2026 landscape for flexible financing so you can work with a broker who understands complex income. It’s time to stop waiting on slow approvals and start moving toward a fast, predictable closing.
Key Takeaways
- Stop letting tax deductions kill your borrowing power by using non-qm loans that verify income through bank statements and property cash flow.
- Identify the specific loan programs that favor entrepreneurs, including DSCR options that ignore personal income entirely.
- Navigate the underwriting process faster by preparing for a pre-flight review of your liquidity and exit strategy.
- Learn when to choose the speed of hard money over the lower long-term costs of a non-QM solution.
- Leverage an investor-focused strategy to structure complex deals that traditional banks aren’t equipped to handle.
What is a Non-QM Loan? Breaking Free from the QM Trap
Banks love their boxes. If you don’t fit the rigid profile of a W-2 employee, they usually show you the door. Non-QM stands for Non-Qualified Mortgage. These are loans that don’t fit the narrow “Ability to Repay” box defined by federal regulators. In 2026, the traditional 30-year fixed mortgage isn’t the only way to build wealth. In fact, for many, it’s a trap. These non-qm loans offer a way out. They prioritize your actual cash flow over the paper-thin version of your income found on a tax return.
The ‘Qualified Mortgage’ (QM) vs. Non-QM Divide
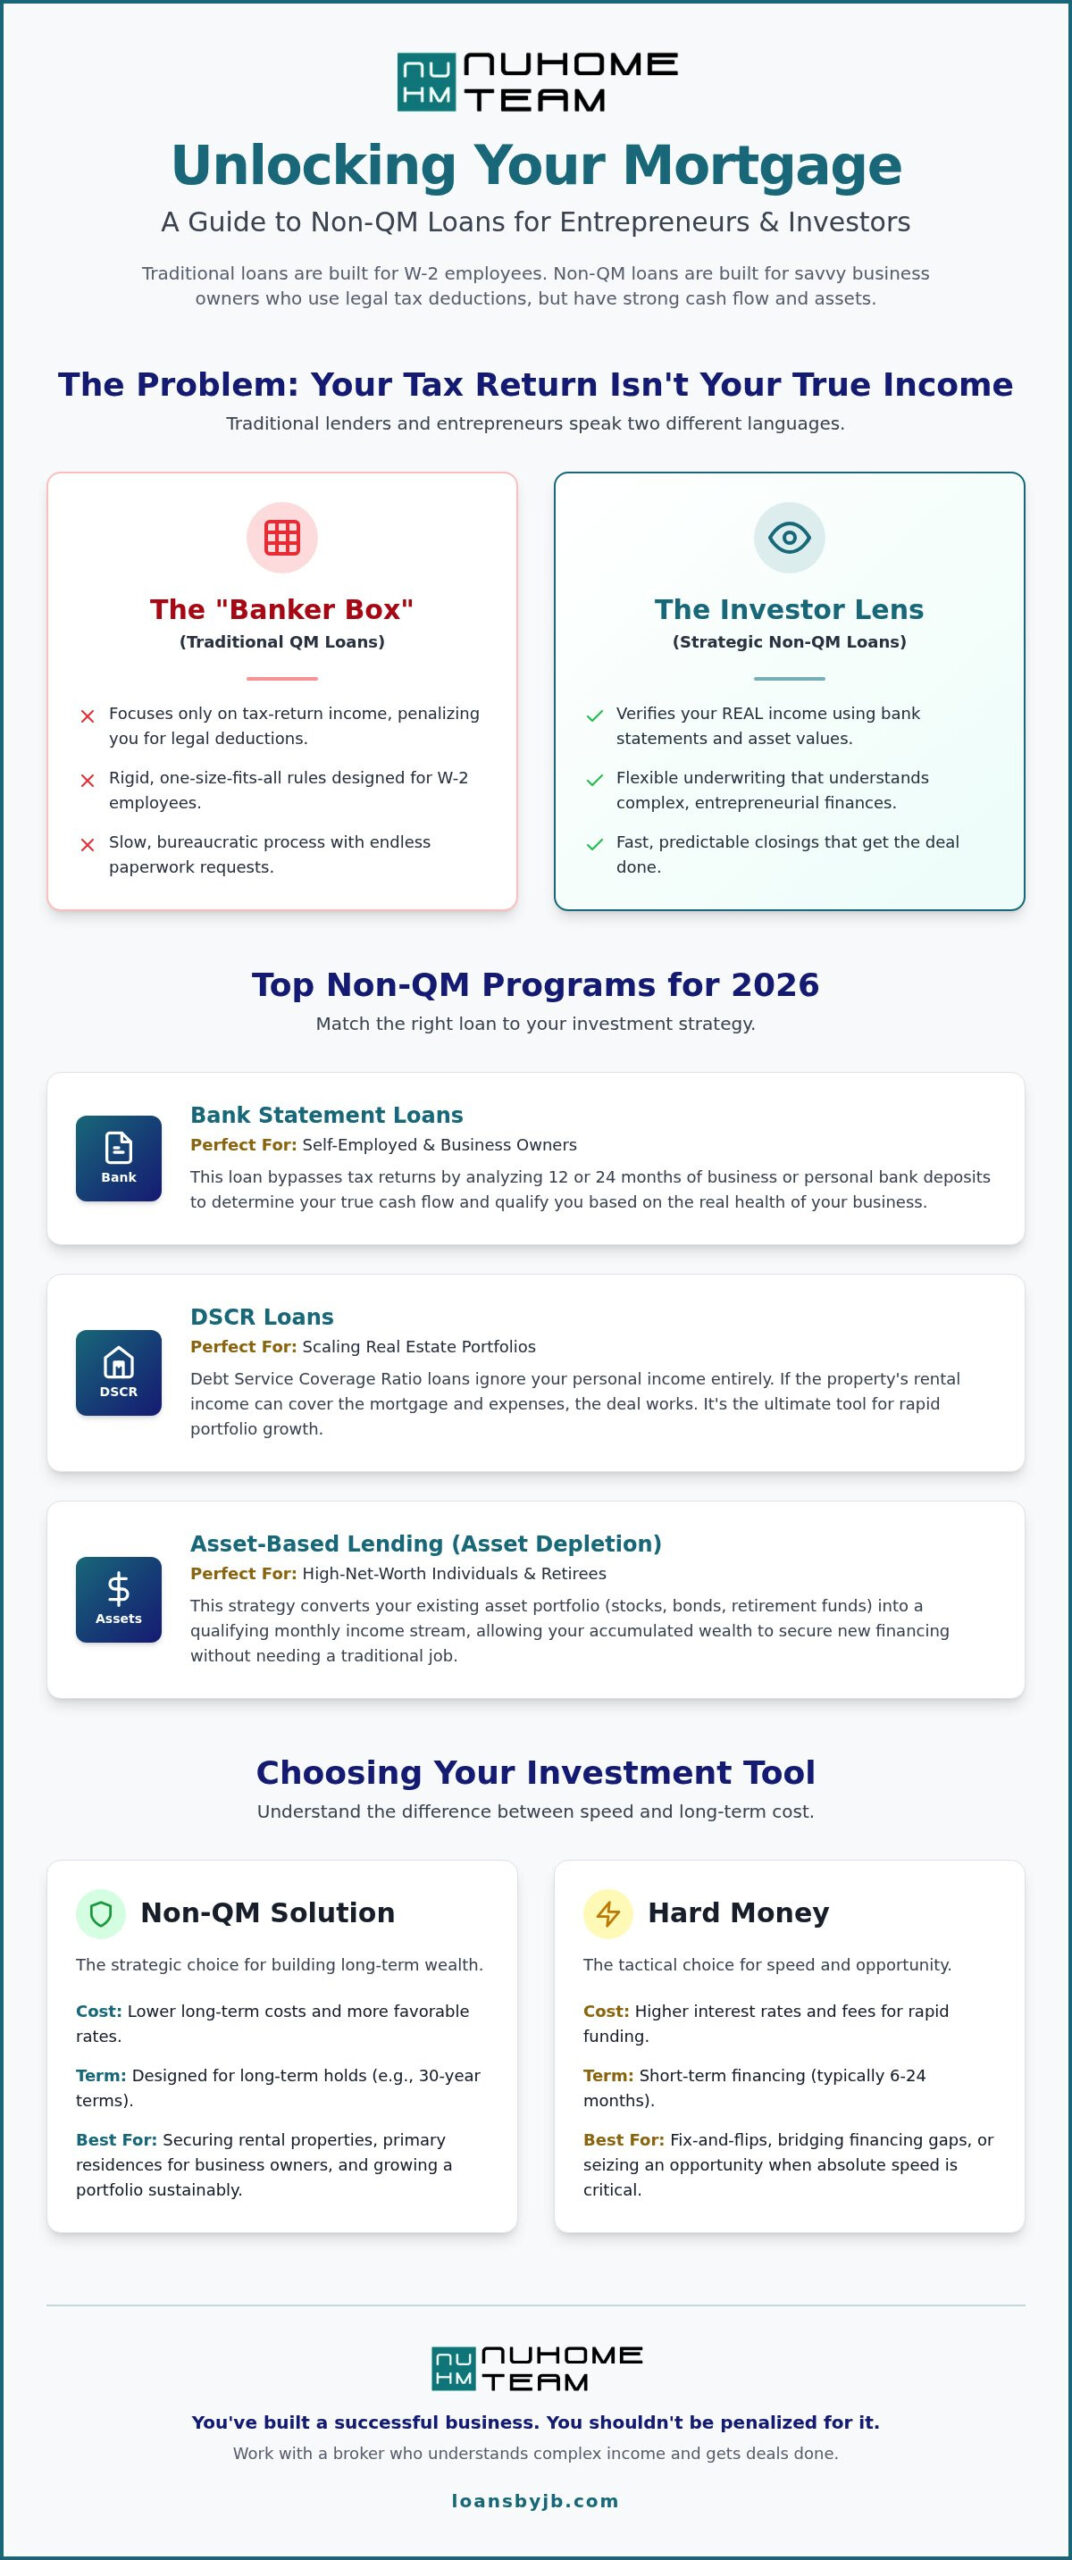
The Qualified Mortgage rules were born from the Dodd-Frank Act to protect banks, not you. This legislation created a rigid “Banker Box” that effectively excludes entrepreneurs and creative investors. We look at your deal through an “Investor Lens” instead. We see the value in your liquidity and your business’s health. Non-QM is a strategic tool for high-liquidity borrowers who require underwriting flexibility beyond standard federal guidelines. It’s about looking at the full picture, not just a single checkbox.
Common Myths About Non-QM Lending
Don’t believe the “Subprime 2.0” noise. Non-QM isn’t about lending to people who can’t pay; it’s about lending to people who pay differently. These programs still require significant assets and solid credit scores. The documentation is flexible, but the standards remain high. While interest rates might look slightly higher on paper, they are often more competitive when you factor in the massive tax savings from your business deductions. You don’t have to choose between a low tax bill and a new home. You can have both.
For self-employed borrowers in Claremont or Upland, this is a game changer. You’ve built a successful business. You shouldn’t be penalized for it. We use non-qm loans to structure winning loan scenarios by focusing on your true buying power. We move fast. We stay predictable. Our team gets you to the closing table while the big banks are still asking for your 2023 1040s. Stop following the herd. The real gold standard is whatever gets the keys in your hand without compromising your tax strategy.
Top Non-QM Programs for 2026: Matching the Loan to Your Strategy
Finding the right loan isn’t about luck. It’s about strategy. Traditional lenders rely on the official definition of a Qualified Mortgage to decide if you’re worthy. We don’t. In 2026, high-performing investors need non-qm loans that reflect their actual financial strength, not just what their tax accountant says. Whether you’re buying a luxury estate in Downey or a rental in Glendora, you need a program that fits your specific cash flow model.
Bank Statement Loans for the Self-Employed
Business owners in Rancho Cucamonga often get the short end of the stick. You have the revenue, but your tax returns show heavy write-offs. A bank statement loan solves this by looking at your actual deposits over the last 12 or 24 months. We analyze the health of your business by seeing the money move in real-time. We can use personal or business statements, depending on which shows the strongest picture of your income. While you can compare these to traditional options in our 30-year fixed mortgage guide, entrepreneurs usually find the flexibility of non-QM far superior for high-value purchases.
DSCR and Asset-Based Lending
Debt Service Coverage Ratio (DSCR) loans are the ultimate weapon for scaling a portfolio. We don’t care about your W-2. We care about the property’s ability to pay for itself. If the rent covers the mortgage and expenses, the deal works. This allows you to close quickly without the standard paperwork mountain. For high-liquidity individuals or retirees, asset depletion strategies turn your existing portfolio into qualifying monthly income. You’ve done the work to build your wealth; now let that wealth work for you. Read more in our DSCR Loan Guide to see how to scale without tax returns.
Jumbo non-qm loans take this a step further for the Southern California market. When you’re eyeing a multi-million dollar property, a standard jumbo loan might require perfect tax returns and massive reserves. Our non-QM jumbo options provide a path forward for those with complex income structures. If you’re ready to stop jumping through bank hoops and start closing deals, reach out to structure your next scenario. We focus on the numbers that actually matter to your bottom line. We prioritize speed and predictability over corporate pleasantries.
The Qualification Roadmap: Navigating the Non-QM Underwriting Maze
Documentation is the next hurdle. Forget the standard two years of tax returns. We focus on the last 12 to 24 months of your actual business activity. While some publications list the Best Non-QM Lenders of 2026, many of those big names still struggle with the nuances of Southern California real estate. You need an appraisal process that understands the local heat in Claremont and Rancho Cucamonga. We use an “Investor Lens” to evaluate property carrying costs and market rent potential rather than just looking at the house next door. This ensures the valuation supports your investment goals.
What Underwriters Actually Look For in 2026
Speed is good. Sloppiness is not. One of the biggest deal-killers is unseasoned funds. If large deposits hit your account right before you apply, traditional underwriters panic. We help you source and season those funds properly before submission. Don’t make the mistake of choosing a generic retail lender. They often treat non-qm loans as a side project and lack the expertise to handle the friction of a complex file. The Investor Lens is the key to passing underwriting. It means we look at the deal the way you do: as a strategic move toward long-term wealth.
Non-QM vs. Hard Money: Choosing Your Best Investment Tool
Speed saves or speed kills. It all depends on your timeline. If you’re standing on the courthouse steps in Upland with a winning bid, you don’t have three weeks to wait for an underwriter to check your bank statements. You need cash now. That’s the domain of private capital. However, if you’re planning to hold that property for the next decade, those double-digit interest rates will eventually hollow out your equity. You need to know exactly when to transition into non-qm loans to protect your long-term margins.
Speed vs. Stability
Hard money is for the sprint. It serves as the Hard Money Loans pillar of a successful fix-and-flip strategy. You get the funds in days, complete your renovations, and move on. It’s about leverage and velocity. Non-QM is for the marathon. In a volatile Southern California market, stability is your best defense against shifting values. If you’re building a portfolio in Rancho Cucamonga or Claremont, you want the predictable payments and lower cost of capital that come with a long-term structure. Our 2026 Private Money Guide breaks down how to use that initial burst of capital to secure the deal before the competition even wakes up.
The cost of capital is the ultimate differentiator. Hard money lenders prioritize the asset over the borrower, which means they charge a premium for that risk and speed. You’ll likely face higher points and rates that reflect the short-term nature of the loan. Non-qm loans sit in the sweet spot. They’re more affordable than hard money but offer far more flexibility than a traditional bank. You’re paying for the ability to use your real cash flow instead of a tax return, but you’re getting a rate that allows for healthy monthly cash flow.
Refinancing Out of Private Capital
The smartest investors use a “buy, rehab, rent, refinance” model. They use private money to buy and fix, then use Non-QM as their “takeout” financing. This move replaces expensive, short-term debt with a stable, 30-year structure. In 2026, the rules around seasoning are critical. Some lenders require you to own the property for 12 months before they’ll recognize the new, improved value for a cash-out refinance. Others might let you move as early as 6 months. This is where experience matters. Justin Brown uses 25 years of industry knowledge to navigate these seasoning requirements. He knows which lenders will credit your hard work and which ones will make you wait. We bridge the gap between your renovation and your long-term wealth.
Don’t let your capital get trapped in high-interest bridge loans. If your project is nearing completion, it’s time to talk about your permanent financing options. Contact us to structure your exit strategy today and lock in the stability your portfolio needs to thrive in the 2026 market.
The LoansByJB Advantage: Why Southern California Investors Choose Us
Banks are focused on their own safety. We’re focused on your growth. When you work with LoansByJB (The Nuhome Team), you aren’t just a number in a digital queue. We don’t just take applications. We structure winning loan scenarios. By using our “Investor Lens,” we evaluate the true potential of a deal. We look at carrying costs, market trends, and your specific exit strategy. Traditional lenders often miss these nuances, but we use non-qm loans to bridge the gap between a “no” and a closed deal.
Our roots are deep in Southern California. We understand the specific market dynamics of Claremont, La Verne, and San Dimas. These aren’t just names on a map to us. They’re neighborhoods where we’ve helped investors scale for decades. Whether you’re looking at a multi-family unit in Upland or a high-value residence in Glendora, our local expertise ensures your financing is as solid as the property itself. We prioritize results over corporate pleasantries. You get the truth, even if it’s blunt.
Experience That Matters
Justin Brown brings over 25 years of industry experience to the table. He’s been a broker, a lender, and an investor himself. This triple-threat perspective is rare. It means he understands the friction you feel when a bank rejects a perfectly good deal because of a tax deduction. A real conversation with a seasoned expert beats an automated rejection every time. LoansByJB (The Nuhome Team) has spent a quarter-century mastering the rules so we know exactly how to navigate them to your advantage. Our commitment to the Southern California community is built on transparency and a proactive approach to problem-solving.
Take the Next Step
Ready to see what your true buying power looks like? Starting your evaluation is simple. We don’t need a mountain of paperwork to give you an honest assessment. For your first consultation with LoansByJB (The Nuhome Team), bring your recent bank statements and a clear idea of your exit strategy. We’ll handle the complex math and the underwriting hurdles that stop other lenders in their tracks. We move at the speed of your business, not the speed of a bank committee.
Stop letting rigid bank rules dictate your investment future. You’ve done the work to build your business and your capital. Now, let’s put it to work. Get your personalized Non-QM strategy from Justin Brown and secure the financing you deserve. We’re here to help you navigate the world of non-qm loans with confidence and speed. Let’s get your next deal to the closing table.
Stop Asking for Permission to Grow
Traditional banks aren’t going to change their rigid ways. They’ll keep looking for reasons to say no while you keep looking for ways to grow. You now have the roadmap to bypass their outdated systems. By choosing non-qm loans, you’re choosing to be evaluated on your actual financial success. You’ve seen how bank statement programs and DSCR models look at your true cash flow. This isn’t just an alternative; it’s the professional standard for the modern investor who refuses to be boxed in.
LoansByJB (The Nuhome Team) brings a specialized “Investor Lens” to every deal we touch. With 25+ years of Southern California expertise and NMLS #1647915, our team understands the nuances of complex income. We don’t fear the friction that stops big-box lenders. Instead, we use it to structure a winning scenario for your primary residence or next investment. You deserve a partner who speaks your language and values your results over corporate paperwork.
Stop settling for ‘No’—Get your Non-QM strategy from LoansByJB (The Nuhome Team) today. You have the vision to see the potential in the market. We have the capital and the expertise to help you capture it. Let’s get to work and close your next deal with the speed and predictability you deserve.
Frequently Asked Questions
Are Non-QM loans more expensive than traditional mortgages?
Yes, they usually carry slightly higher interest rates than conventional mortgages. You’re paying for the ability to use flexible documentation instead of rigid tax returns. For an investor in San Dimas, the slightly higher cost is often offset by the ability to close a deal that a big bank would reject. These non-qm loans are a strategic investment tool, not a last resort for bad credit.
Can I get a Non-QM loan with a 620 credit score in 2026?
Yes, it is possible. While traditional banks might demand a perfect score, we look at your liquidity and your overall financial story. A 620 score might require a larger down payment or more significant reserves to offset the risk. In markets like Upland, we focus on your ability to handle the debt through cash flow. We prioritize a real conversation over an automated rejection every time.
What is the typical down payment for a bank statement loan?
You should expect to put down between 10% and 20%. The exact number depends on your credit score and the consistency of your business deposits over the last 12 to 24 months. If you’re buying a high-value property in Glendora, a 20% down payment often unlocks much more competitive interest rates. We’ll help you analyze which structure protects your cash reserves while securing the best possible terms.
How long does it take to close a Non-QM loan compared to a conventional one?
We typically close in 21 to 30 days. This is often faster than conventional loans because we don’t have to wait for the federal bureaucracy of Fannie Mae or Freddie Mac. Our pre-flight review process identifies potential hurdles before they become deal-killers. For an investor in Rancho Cucamonga, this speed means you can compete with cash buyers and win more deals in a tight market.
Do I need to be a full-time real estate investor to qualify for DSCR?
No, you don’t. DSCR loans are available to anyone who is buying an investment property that generates enough rent to cover the mortgage payment. You could be a W-2 employee in Claremont looking to buy your first rental. We don’t look at your personal debt-to-income ratio. We look at the property’s performance. It’s a powerful way to scale a portfolio without using your personal income.
What happens if my business has one bad month of bank statements?
One bad month isn’t a deal-killer. We analyze the 12 or 24-month average of your deposits to determine your qualifying income. If your business is seasonal or had a one-time expense, we use a Letter of Explanation to provide context to the underwriter. We look at the health of your business over the long haul. Our goal is to find a way to make the numbers work for you.
Can I use Non-QM for a high-value Jumbo property in Southern California?
Yes, this is where non-qm loans truly shine. High-value properties in luxury Southern California markets like La Verne often exceed standard loan limits. If you’re self-employed and buying a multi-million dollar home, traditional jumbo rules are incredibly restrictive. We use non-QM structures to verify your income through bank statements. This allows you to secure high-value financing without the W-2 headache that stops traditional banks.
Is there a prepayment penalty on Non-QM loans?
For investment properties, prepayment penalties are common and typically last between one and three years. This helps keep your initial interest rate lower. However, if you’re using a loan for your primary residence, federal law usually prohibits these penalties. We’re straight-shooters. We’ll disclose every detail of your loan structure upfront so there are no surprises when you’re ready to refinance or sell your property.
Need the mortgage math checked?
Talk through the loan before you guess.
Use the estimator, request a refinance quote, or book a call with The Nuhome Team. We will help you compare the options that actually fit the file.
This is not a commitment to lend. Approval, terms, and pricing depend on credit, income, assets, property, and program guidelines.