Why are you still waiting on a callback from a bank that treats your complex tax return like a crime scene? In the 2026 Southern California market, sticking with a big institution often means dealing with rigid underwriting and glacial communication. The mortgage broker vs bank debate isn’t just about interest rates anymore. It’s about who actually has the tools to close your deal. With median home prices hitting $855,300 and rates hovering around 7.25%, you can’t afford to be sidelined by corporate red tape.
You deserve a partner who understands that non-traditional income isn’t a red flag. You’ve likely felt the sting of being a savvy investor or self-employed professional ignored by traditional lenders. This article promises to show you why a strategic broker outperforms big banks for complex 2026 loan scenarios. We’ll preview the essential checklist for faster closing times, access to specialized DSCR products, and how to navigate new California regulations like Proposition 37. It’s time for a straight-shooter’s guide to winning in this market.
Key Takeaways
- Stop settling for “no” from rigid institutions that only want easy W2 files. Learn why the mortgage broker vs bank landscape has shifted in 2026 toward flexible, independent strategies.
- Vet your lending partner with a 5-point checklist that demands multi-cycle experience and a deep bench of renovation products like FHA 203k loans.
- Identify exactly where big banks fail the modern Southern California entrepreneur and how to bypass the restrictive “W2-only” underwriting mindset.
- Discover how to secure jumbo loans for investment properties using strategic products that don’t require traditional tax returns or massive corporate deposits.
- Master the first consultation by asking high-impact questions that reveal if a loan officer is a corporate gatekeeper or a street-smart local problem-solver.
Beyond the Branch: Why the Bank vs. Broker Debate Changed in 2026
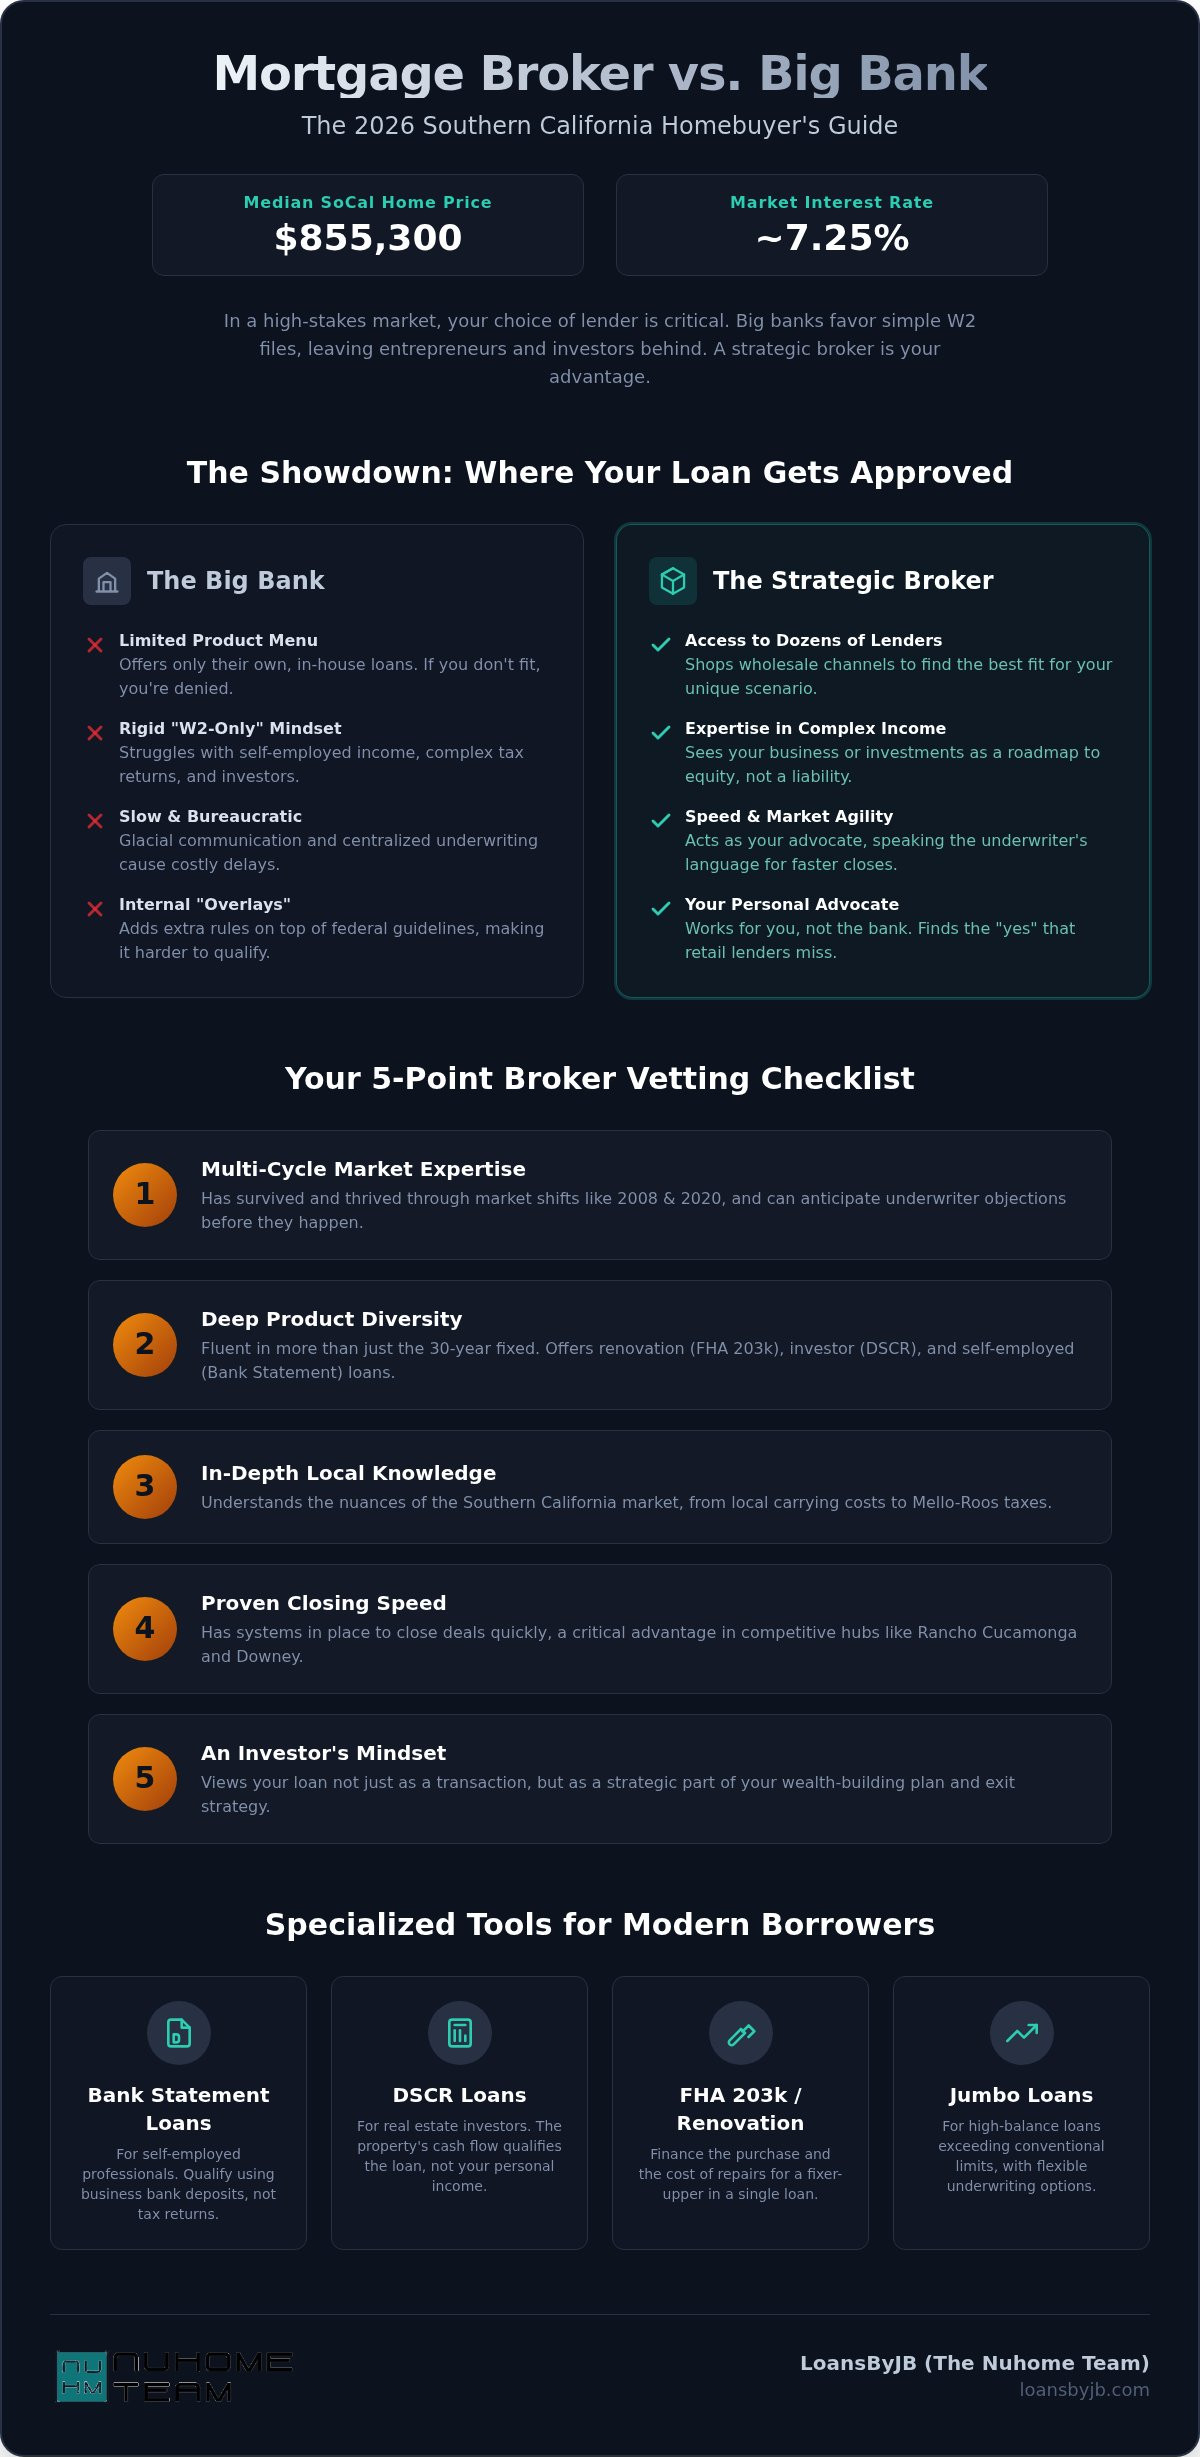
2026 isn’t the same market your parents bought in. Banks are retreating into a narrow “box” to protect their balance sheets. If you don’t fit a standard, clean W2 profile, you’re effectively invisible to them. The mortgage broker vs bank choice is no longer about a slight difference in fees; it’s a choice between a corporate gatekeeper and a strategic advocate. Banks sell products they own. Brokers hunt for the strategy that wins.
A captive loan officer at a big bank works for the institution, not you. They are limited to one menu. To understand the alternative, look at What is a Mortgage Broker? It’s an independent expert who shops dozens of wholesale channels to find the specific fit for your scenario. Direct funding sounds stable until you realize it’s tied to one set of rigid, unyielding rules. In a volatile market, that rigidity is your biggest risk.
The Problem with Big Bank Underwriting
Banks rely heavily on “overlays.” These are extra, internal rules layered on top of federal guidelines. Even if you qualify for a 30 Year Fixed Mortgage under federal standards, a bank might reject you because they don’t like your specific industry or your Southern California high-balance loan amount. This “investor lens” is missing from corporate banking cubicles. They see a complex tax return as a liability. We see it as a roadmap to equity. For self-employed earners, bank underwriting feels like a trial, not a service.
The Broker Advantage in a Volatile Market
Market volatility requires absolute speed. In competitive Southern California hubs like Rancho Cucamonga and Downey, you can’t wait three days for a bank’s “centralized underwriting” team to respond. Brokers act as a vital buffer between you and the money. We speak the language of the underwriter and present your file in the best light. Because we access specialized channels like Non-QM and DSCR Loans, we can find the “yes” that a retail bank missed. We don’t wait for the bank to approve your lifestyle; we find a lender that already values it.
The Experienced Mortgage Broker Checklist: 5 Non-Negotiables
Don’t hire someone just because they have a license and a pulse. In a market where Southern California median home prices hit $855,300, a license is the bare minimum requirement. You need a veteran who knows how to navigate the mortgage broker vs bank divide when a deal gets messy. Use this checklist to vet your next loan officer. If they can’t check every box, walk away. Your equity depends on their expertise.
1. Multi-Cycle Market Expertise
You need a broker who has survived 2008, navigated 2020, and mastered the 2026 shifts. Experience isn’t just a number; it’s the ability to anticipate an underwriter’s rejection before the file even hits their desk. A seasoned pro looks at your deal through an “investor lens.” They don’t just see a loan. They see an exit strategy. This level of foresight is how we close deals that banks leave for dead. As a consumer protection regulator explains, brokers have the flexibility to shop around, but only the experienced ones know which specific door to knock on first.
2. Product Diversity Beyond the 30-Year Fixed
Standard loans are fine for standard people. But if you’re a business owner or an active investor, you need more. Demand a deep bench of renovation products like FHA 203k loans or Homestyle options. A real expert understands renovation math and how it impacts your long-term value. They should also be fluent in specialized tools like DSCR loans for scaling portfolios without tax returns. If you’re self-employed, don’t let a bank’s W2 bias stop you. Look for a specialist in mortgage for self-employed borrowers who can use bank statements to prove your worth. Finally, ensure they have a clear jumbo loan refinance strategy ready for when market conditions shift.
Southern California is its own beast. Your broker must have in-house knowledge of local property carrying costs, Mello-Roos taxes, and high-balance limits. They should be a “straight-shooter” who prioritizes results over corporate pleasantries. You don’t need a friend; you need a closer. If you want to see how a 25-year veteran handles these complexities, talk to LoansByJB (The Nuhome Team) today. We focus on the strategy that actually gets you the keys.
Direct Comparison: Where Banks Win vs. Where Brokers Dominate
Banks love the path of least resistance. If you have a standard W2 job, a perfect credit score, and a massive deposit sitting in their vault, a bank might offer a smooth experience. They want the easy files that fit their rigid, pre-defined boxes. But Southern California isn’t a “standard” market. The mortgage broker vs bank decision usually comes down to how much you value your time and your sanity. If your tax returns are more than two pages long, the bank’s automated system will likely flag you as a risk. We see you as an opportunity.
Pricing and Rates: The Wholesale Secret
Banks sell at retail prices. They have to pay for marble lobbies, thousands of middle managers, and national ad campaigns. You pay for that overhead through higher rates and hidden margins. Brokers work differently. We access wholesale channels and “par rates” that aren’t available to the general public. While a bank hides their profit in a proprietary rate, a broker’s compensation is transparently disclosed on your loan estimate. Sometimes, a slightly higher rate is worth a guaranteed “close” on a complex deal that a retail bank would have rejected after three weeks of silence. You aren’t just buying a rate; you’re buying a result.
Service and Speed: The Local Edge
Try calling a big bank on a Saturday morning when an appraisal comes in low. You’ll get an 800-number and a “we’ll get back to you in two business days” recording. In high-demand areas like Upland, San Dimas, and Glendora, that delay is a deal-killer. A local broker provides a direct cell phone number and a sense of urgency. If a specific lender gets cold feet about a property condition, a broker can pivot the entire file to a new wholesale partner in 24 hours. We understand the local market nuances that a desk jockey in a different time zone will never grasp. We don’t just process paperwork. We solve problems in real-time.
People often ask who actually pays the broker. In most scenarios, the wholesale lender pays the broker’s fee. It is built into the pricing just like the bank’s internal profit margin. The difference is that the broker works for you, not the institution. You get an advocate who hunts for the best strategy while the bank only hunts for its own bottom line. Don’t let a corporate gatekeeper dictate your financial future when you can have a local expert fighting in your corner.
Handling Complex Scenarios: Why Southern California Investors Choose Brokers
Banks prioritize safety over strategy. They want the borrower who has been at the same desk for twenty years. If you’re a high-net-worth individual with complex tax returns, you’re a headache for a retail loan officer. This is where the mortgage broker vs bank divide becomes a wall for most business owners. In 2026, Southern California real estate demands a level of surgical precision that corporate banking simply isn’t built to provide. You need a partner who sees your business success as an asset, not a liability.
The Self-Employed Struggle
Banks operate with a W2-only mindset that effectively punishes the modern entrepreneur. If you’ve spent years building a business and optimizing your tax returns, a traditional bank sees your legal deductions as a lack of income. They misinterpret business write-offs as financial weakness. A broker works differently. We use specialized products to bridge the gap between your tax returns and your actual buying power. We look for the following indicators of financial health:
- Total business deposits over a 12 to 24-month period.
- Consistent cash flow rather than just taxable net income.
- Asset liquidity that traditional underwriting often ignores.
An experienced broker translates your business success into a language that wholesale underwriters actually value. This type of niche expertise is invaluable; for instance, medical professionals often rely on Mortgages for Doctors to navigate their unique income structures, much like we help Southern California entrepreneurs find the right fit. Instead of begging a bank to understand your P&L statement, we place your file with a lender that specializes in bank statement loans to ensure your true income is the basis for your approval.
Scaling a portfolio in 2026 requires more than just a down payment. You need tactical liquidity. This is why we leverage adjustable rate mortgages to keep monthly costs manageable while you wait for the next market cycle. For those targeting high-cost areas like Claremont and La Verne, renovation loans are the ultimate tool to create forced equity in a tight inventory environment. We help you structure the deal so the renovation costs are baked into the financing, allowing you to maximize your cash on hand.
If you are moving into the high-end market, you can secure a jumbo loan for investment property California without providing personal tax returns. We use DSCR (Debt Service Coverage Ratio) loans to qualify the property based on its own rental income. This removes the personal income hurdle entirely. It is about optimizing carrying costs to ensure your structure passes strict 2026 underwriting standards. Don’t let a bank’s limited menu starve your growth. Build your investor strategy with LoansByJB (The Nuhome Team) and stop waiting for permission to scale.
Closing Your Deal: How to Leverage an Investor-Focused Broker
Stop waiting for a bank to “approve” your lifestyle. If you’ve been sidelined by a corporate institution, you know the frustration of being treated like a line item in a spreadsheet. The mortgage broker vs bank choice ends when you realize that one sells a product while the other sells a result. In 2026, Southern California’s market is too aggressive for half-measures. You need a partner who understands the difference between a hurdle and a dead end.
The “Real Conversation” Framework
Your first call with a loan officer is an interview. If they only ask about your credit score and W2, they are checking boxes, not building a strategy. A true investor-focused broker asks about your five-year exit strategy. They want to know if you’re looking for long-term cash flow or a short-term equity play. Red flags in corporate loan officers include a heavy reliance on scripts and an immediate “no” to anything outside of a standard Fannie Mae box. LoansByJB (The Nuhome Team) applies an investor lens to every transaction. With 25 plus years of experience, Justin Brown and our team look at your financial profile as a puzzle to be solved, not a reason to reject. We prioritize street-smart relatability over corporate pleasantries.
Start Your 2026 Strategy
Move from shopping for rates to shopping for the right structure. A lower rate on a loan that never closes is worthless. In competitive pockets like Downey or Rancho Cucamonga, decisive action is the only currency that matters. Sellers in these areas won’t wait for a bank’s thirty-day underwriting cycle. They want to see a solid approval from someone who knows the local dirt. To prep your complex file for a 2026 approval, organize your bank statements and LLC documents now. Even if we use a product that ignores tax returns, having a clean financial package allows us to move with speed.
Stop playing bank games. You’ve worked hard to build your wealth; don’t let a rigid institution tell you how to use it. If you’re ready for a straight-shooter who values your time and your goals, it’s time to get a professional on your side. We focus on the strategy that actually closes. Reach out to LoansByJB (The Nuhome Team) to secure an advocate who understands the nuances of the Southern California market and get the keys you’ve been waiting for.
Take Control of Your 2026 Lending Strategy
The 2026 Southern California market moves too fast for corporate red tape. You’ve seen how the mortgage broker vs bank landscape has shifted toward those who prioritize speed and specialized product knowledge. Success in cities like Rancho Cucamonga and Downey requires more than a simple approval; it requires a loan structure that protects your long-term exit strategy. Whether you’re a self-employed professional or a seasoned investor, you need a partner who understands that complex tax returns are a roadmap to wealth, not a reason for rejection.
Stop letting rigid institutions dictate your buying power. Leverage 25 plus years of street-smart expertise and deep Southern California roots to navigate these volatile shifts. We specialize in the complex investor and self-employed scenarios that big banks ignore. It’s time to move past the 800-numbers and start a real conversation about your future. You deserve an advocate who values your time and understands the local dirt.
Ready to win? Get a straight-shooting strategy for your Southern California loan today. Your next property is waiting. We have the tools and the grit to help you claim it.
Frequently Asked Questions
Is it cheaper to use a mortgage broker than a bank in 2026?
It’s often more cost-effective because brokers shop wholesale markets that aren’t available to the general public. While a bank’s retail pricing covers massive corporate overhead, brokers access “par rates” through multiple wholesale channels. Industry professionals report that the rate difference can save borrowers between $10,000 and $30,000 over the life of a loan. In the 2026 mortgage broker vs bank landscape, lower administrative fees also help keep your closing costs manageable.
Do mortgage brokers have better rates than banks for Jumbo loans?
Brokers frequently dominate the Jumbo market in Southern California because they aren’t restricted to one bank’s internal appetite. High-cost areas like Claremont and La Verne require high-balance loans that often trigger strict bank overlays. A broker accesses specialized wholesale lenders who have a higher appetite for these larger amounts. This competition among lenders often leads to more aggressive pricing and flexible terms that a local branch simply cannot match.
Can a mortgage broker help if my bank already denied my application?
Yes, a bank denial is often just the beginning for a broker. Banks use rigid internal rules called “overlays” that reject borrowers who meet federal guidelines but don’t fit the bank’s specific preference. We specialize in complex scenarios, using Non-QM Loans or bank statement programs to secure approvals. If your income structure or property type scared off a retail lender, we pivot your file to a wholesale partner that values your specific financial profile.
What happens if a broker can’t find a lender for my complex scenario?
If a standard wholesale lender isn’t a fit, a veteran broker pivots to Hard Money or Private Money Loans. We don’t just leave you stranded. We look at your five-year exit strategy and use these alternative products as a bridge to get you into the property. Once you’ve established equity or resolved the hurdle, we move you into a traditional 30 Year Fixed Mortgage. It’s about building a path, not just processing a file.
How much does a mortgage broker charge in Southern California?
Most brokers are compensated by the wholesale lender, meaning there is often no out-of-pocket fee for the borrower. This compensation is built into the interest rate and is fully disclosed on your Loan Estimate. In some specialized cases, a borrower may pay a direct fee to secure a specific wholesale rate. We maintain total transparency because results matter more than corporate games. You’ll know exactly where every dollar goes before you sign anything.
What is the biggest risk of using a bank for a self-employed mortgage?
The biggest risk is the “W2 bias” that misinterprets your business success as financial weakness. Banks typically look at your bottom-line taxable income after deductions, which can artificially lower your buying power. A broker uses an investor lens to evaluate your actual cash flow. We use bank statement programs to prove your ability to repay without letting legal tax write-offs disqualify you from the home you’ve earned in Rancho Cucamonga or Glendora.
How long does it take to close a loan with a broker vs a bank?
Brokers generally close faster because they bypass the layers of centralized corporate management found in big banks. While a bank might take 45 to 60 days to navigate their internal red tape, a proactive broker can often close a deal in 21 to 30 days. Our local roots in Downey and San Dimas mean we have direct relationships with appraisers and title officers who understand the urgency of the Southern California market.
Can a broker help with renovation loans like the FHA 203k?
Absolutely. Specializing in FHA 203k and Homestyle Renovation Loans is a core part of our local strategy. Most traditional banks avoid these products because they require extra work to manage the construction draw process. We embrace that complexity. We help you navigate the math to ensure you’re creating forced equity in competitive markets like Upland. We don’t just find the loan; we help you manage the strategy to win.
Need the mortgage math checked?
Talk through the loan before you guess.
Use the estimator, request a refinance quote, or book a call with The Nuhome Team. We will help you compare the options that actually fit the file.
This is not a commitment to lend. Approval, terms, and pricing depend on credit, income, assets, property, and program guidelines.