Hidden fees in mortgage loans in San Dimas may appear as application, settlement, valuation, legal, or document charges. Some offers bundle these costs, while others list them separately. A fee described as waived may also depend on what the offer includes.
It’s easy to focus on the interest rate and miss the smaller line items. The real comparison is the full cost of the loan, including charges due upfront and any ongoing fees. This article explains which costs to look for, how bundled fees can make mortgage offers harder to compare, and what to review before choosing a mortgage. No guesswork, just a clear look at the numbers and terms in front of you.
Key Takeaways
- Look beyond the interest rate and review each listed charge, including application, settlement, valuation, and document fees.
- Compare bundled and itemized costs so you can see what each loan offer includes.
- Separate upfront charges from ongoing fees to understand the loan’s costs over time.
- Use a side-by-side example to see how fees can affect the total cost of competing offers.
- Consider whether a mortgage advisor can help you make sense of fees across different loan options.
Which mortgage fees should San Dimas borrowers check?
Mortgage fees can be hard to compare when charges are bundled or described broadly. Hidden fees in mortgage loans in San Dimas may include service or administrative charges, or insurance you did not request. Review each line item, not just the total on the first page.
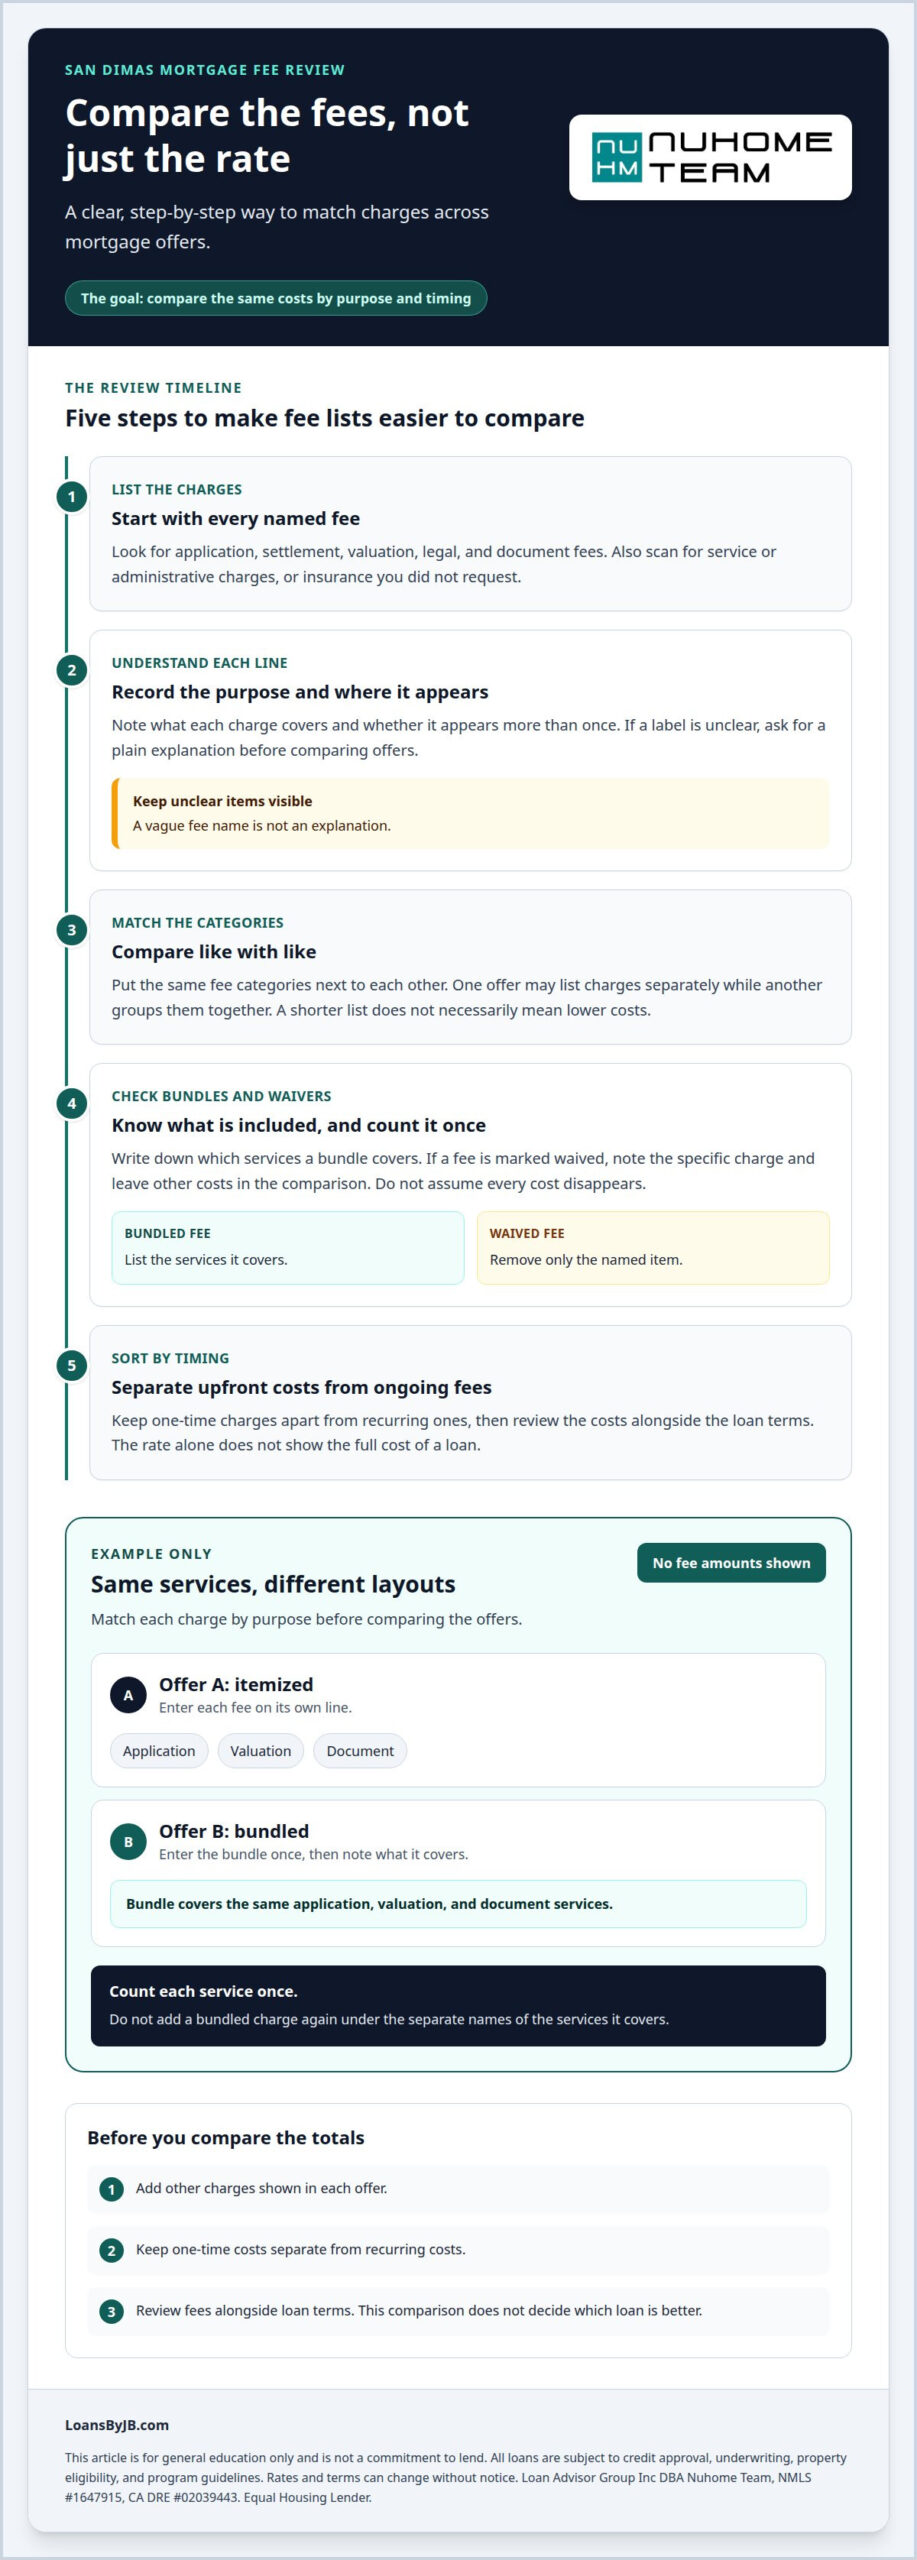
Start with upfront costs. Look for application, settlement, valuation, legal, and document fees. For each charge, note its stated purpose and whether it appears in more than one place. If a label is unclear, ask for a plain explanation before comparing offers. A vague name is not an adequate explanation.
Next, compare the same categories across each offer. Some lenders bundle fees, while others list them separately, so a shorter list does not necessarily mean lower costs. Write down which services a bundle covers. If a promotion waives a fee, record the specific charge waived and note any remaining costs. Do not assume “waived fees” means every cost disappears.
Keep your comparison simple: identify each charge, its purpose, and whether it is included or separate. This gives you a clearer basis for reviewing offers in San Dimas and identifying costs that need an explanation before you decide.
What might those fees look like in an example?
Example only. Compare two sample mortgage offers for the same borrower. Offer A lists an application charge, a valuation charge, and a document charge separately. Offer B shows one bundled charge covering those same services. The different layouts can make a quick glance misleading, so first match each charge by purpose.
For a simple comparison, give each offer its own worksheet column. In Offer A, enter each fee on a separate line. In Offer B, enter the bundle on one line, then note the services it covers. Count each service once. Do not add the bundled amount again under its separate names, or you will count the same costs twice.
Add any other charges shown in each offer, keeping one-time costs separate from recurring ones. If a fee is marked waived, subtract only that named item from the comparison and leave other charges in place. This example does not determine which loan is better. It shows how to make cost lists comparable, then review them alongside the loan terms and how each charge is applied.
Who does this approach fit, and who does it not fit?
This approach can help San Dimas borrowers compare mortgage offers or review a loan estimate before choosing financing. It can help first-time buyers spot charges they might overlook and homeowners weighing a refinance distinguish upfront expenses from recurring costs.
The same fee-review approach applies when comparing a California refinance or HELOC alongside a purchase loan.
This is useful when offers present fees differently. One may list charges line by line, while another groups them together. Sorting fees by purpose and timing makes the comparison clearer, but does not determine which loan is right for you. Loan terms and recurring costs matter too.
This method is not a substitute for comparing interest rates, reviewing full loan documents, or consulting an attorney or CPA about legal or tax questions. The rate alone does not show the full cost of a loan.
If fee descriptions still look unclear, a mortgage advisor can help explain how charges fit into the offers you’re comparing. Discuss your mortgage options when you want help looking at the full picture.
How can LoansByJB (The Nuhome Team) help?
I can help you make sense of mortgage fee lists. A mortgage review can separate upfront charges from recurring costs, explain how a fee is described, and show which costs appear in each offer. The goal is a practical comparison, not a guess based on the headline rate.
Bring the loan estimates and fee worksheets you are reviewing. I can walk through the entries with you, identify items that need a clear explanation, and organize costs so you can compare the same categories across offers. If a charge is bundled, focus on what the bundle covers and whether other costs appear separately. Different labels do not have to derail the comparison.
I can discuss mortgage choices including a 30 Year Fixed Mortgage, 15 Year Fixed Mortgage, FHA Loans, and VA Loans. Review fees alongside the full offer, including its loan terms. A fee comparison helps explain costs, but it doesn’t replace a review of the loan as a whole.
Contact me to talk through the fees in your mortgage offers.
Make your next mortgage decision with clarity
Use your review to set a clear standard for the next step. If a charge is hard to explain, keep it visible in your comparison instead of letting it disappear inside a bundle. A clear record of questions and answers can help you decide whether an offer fits your plans. That is the practical value of reviewing hidden fees in mortgage loans in San Dimas.
You don’t need to make the decision from a headline rate alone. Consider the loan terms, the costs, and what matters most to your household. If you want to talk through your options, start a conversation about your mortgage offer.
A thoughtful review can help you make a more informed decision about your next step.
This article is for general education only and is not a commitment to lend. All loans are subject to credit approval, underwriting, property eligibility, and program guidelines. Rates and terms can change without notice. LoansByJB (The Nuhome Team), NMLS #1647915, CA DRE #02039443. Equal Housing Lender.
Need the mortgage math checked?
Talk through the loan before you guess.
Use the estimator, request a refinance quote, or book a call with The Nuhome Team. We will help you compare the options that actually fit the file.
This is not a commitment to lend. Approval, terms, and pricing depend on credit, income, assets, property, and program guidelines.